

DATA ASSIMILATION
327
n
ero means.) Then, the covariance amo
Observations y a d their model simulation’s equivalent m could be
st
17) and their respective uncertainties r and p,
y s r
m s p
(22)
To first approximation, we may assume s, r, and p to have zero means and to
be uncorrelated with each other. (See section 5.2.5 for dealing with nonz
ng these elements can be written as,
T
T
T
T
T
T
T
T
mm
ss
pp
ym
ss
(23)
yy
ss
rr
where brackets denote statistical expectation. Assuming ergodicity and
tationarity, quantities on the left hand side co
the data and model estimates in time. Then,
s
uld be estimated by averaging
T
T
T
T
T
T
rr
yy
ym
pp
mm
ym
(24)
The former is a direct estimate of data er
ror covariance matrix R, while
the latter provides an indirect estimate of process noise covariance Q.
amely, given a process noise model (u in Eq
corresponding model simulation error can be estimated using standard
met
N
1) and its covariance Q, the
hods. In particular, using the notation defined in Eq (1), the stationary
limit of such error
sim
P is the solution to the Lyapunov Equation,
sim
sim T
T
P
AP A GQG
(25)
which is related to the empirical estimate Eq (24) by,
sim T
T
HP H
pp
(26)
Eq
calibrate the process noise
s (24), (25) and (26) provide a means to
ltimetric sea level data with a coarse (1º)
ariability that constitutes the model’s representation error
(Se
estimate Q.
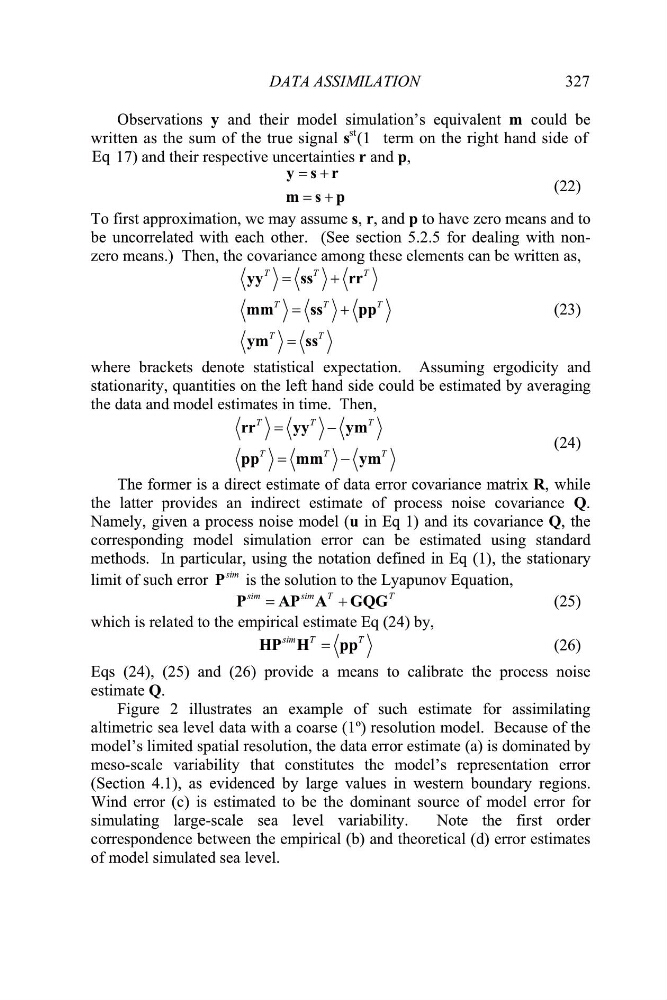
Figure 2 illustrates an example of such estimate for assimilating
a
resolution model. Because of the
model’s limited spatial resolution, the data error estimate (a) is dominated by
meso-scale v
ction 4.1), as evidenced by large values in western boundary regions.
Wind error (c) is estimated to be the dominant source of model error for
simulating large-scale sea level variability.
Note the first order
correspondence between the empirical (b) and theoretical (d) error estimates
of model simulated sea level.
written as the sum of the true signal s (1 term on the right hand side of
Eq