

Digital Signal Processing 9.5 Optimal Signal Estimation 221
Part A | 9.5
The above holds since y.t/ D u.t/ C v .t/ and u.t/ D
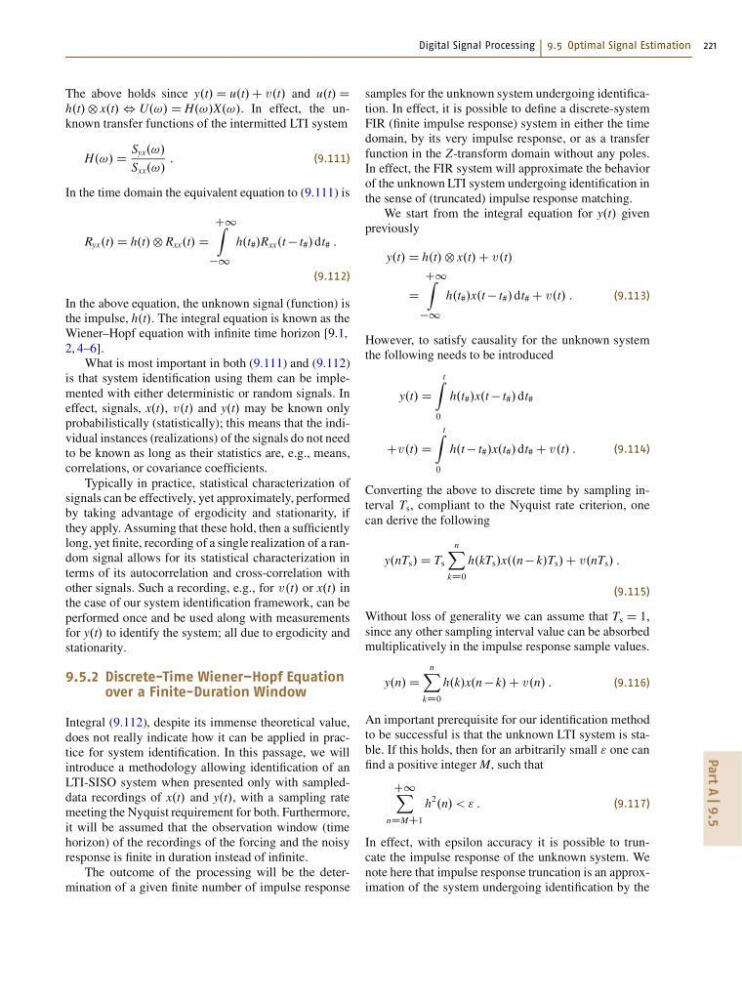
h.t/ ˝ x.t/ , U.!/ D H.!/X.!/. In effect, the unknown transfer functions of the intermitted LTI system
H.!/ D
S yx .!/
S xx .!/
:
(9.111)
In the time domain the equivalent equation to (9.111) is
R yx .t/ D h.t/ ˝ R xx .t/ D
C1 Z
1
h.t # /R xx .t t # / dt # :
(9.112)
In the above equation, the unknown signal (function) is
the impulse, h.t/. The integral equation is known as the
Wiener–Hopf equation with infinite time horizon [9.1,
2, 4–6].
What is most important in both (9.111) and (9.112)
is that system identification using them can be implemented with either deterministic or random signals. In
effect, signals, x.t/, v .t/ and y.t/ may be known only
probabilistically (statistically); this means that the individual instances (realizations) of the signals do not need
to be known as long as their statistics are, e.g., means,
correlations, or covariance coefficients.
Typically in practice, statistical characterization of
signals can be effectively, yet approximately, performed
by taking advantage of ergodicity and stationarity, if
they apply. Assuming that these hold, then a sufficiently
long, yet finite, recording of a single realization of a random signal allows for its statistical characterization in
terms of its autocorrelation and cross-correlation with
other signals. Such a recording, e.g., for v .t/ or x.t/ in
the case of our system identification framework, can be
performed once and be used along with measurements
for y.t/ to identify the system; all due to ergodicity and
stationarity.
9.5.2 Discrete-Time Wiener–Hopf Equation
over a Finite-Duration Window
Integral (9.112), despite its immense theoretical value,
does not really indicate how it can be applied in practice for system identification. In this passage, we will
introduce a methodology allowing identification of an
LTI-SISO system when presented only with sampleddata recordings of x.t/ and y.t/, with a sampling rate
meeting the Nyquist requirement for both. Furthermore,
it will be assumed that the observation window (time
horizon) of the recordings of the forcing and the noisy
response is finite in duration instead of infinite.
The outcome of the processing will be the determination of a given finite number of impulse response
samples for the unknown system undergoing identification. In effect, it is possible to define a discrete-system
FIR (finite impulse response) system in either the time
domain, by its very impulse response, or as a transfer
function in the Z-transform domain without any poles.
In effect, the FIR system will approximate the behavior
of the unknown LTI system undergoing identification in
the sense of (truncated) impulse response matching.
We start from the integral equation for y.t/ given
previously
y.t/ D h.t/ ˝ x.t/ C v .t/
D
C1 Z
1
h.t # /x.t t # / dt # C v .t/ :
(9.113)
However, to satisfy causality for the unknown system
the following needs to be introduced
y.t/ D
t
Z
0
h.t # /x.t t # / dt #
Cv .t/ D
t
Z
0
h.t t # /x.t # / dt # C v .t/ :
(9.114)
Converting the above to discrete time by sampling interval T s , compliant to the Nyquist rate criterion, one
can derive the following
y.nT s / D T s
n
X
kD0
h.kT s /x..n k/T s / C v .nT s / :
(9.115)
Without loss of generality we can assume that T s D 1,
since any other sampling interval value can be absorbed
multiplicatively in the impulse response sample values.
y.n/ D
n
X
kD0
h.k/x.n k/ C v .n/ :
(9.116)
An important prerequisite for our identification method
to be successful is that the unknown LTI system is stable. If this holds, then for an arbitrarily small " one can
find a positive integer M, such that
C1 X
nDMC1
h
2
.n/ < " :
(9.117)
In effect, with epsilon accuracy it is possible to truncate the impulse response of the unknown system. We
note here that impulse response truncation is an approximation of the system undergoing identification by the