

449
nature. Therefore, climatic time series, as well as most other time series
from nature or the laboratory, are more likely to be generated by forced
dissipative systems (Lorenz 1963; Ghil and Childress 1987, Ch. 5). The
invariant sets associated with irregularity here are "strange attractors"
(Ruelle and Takens 1971), towards which all solutions tendasymptotically, i.e., long-term irregular behavior in such systems is associated with
these attractors. These objects are also fractal, although rigorous proofs to
this effect have been much harder to give than in the case of Hamiltonian
cantori (Guckenheimer and Holmes 1983, Lasota and Mackey 1994).
The idea of Mane (1981), Ruelle (1981) and Takens (1981) - as recently
developed further by Sauer et al. (1991) - was that a single observed
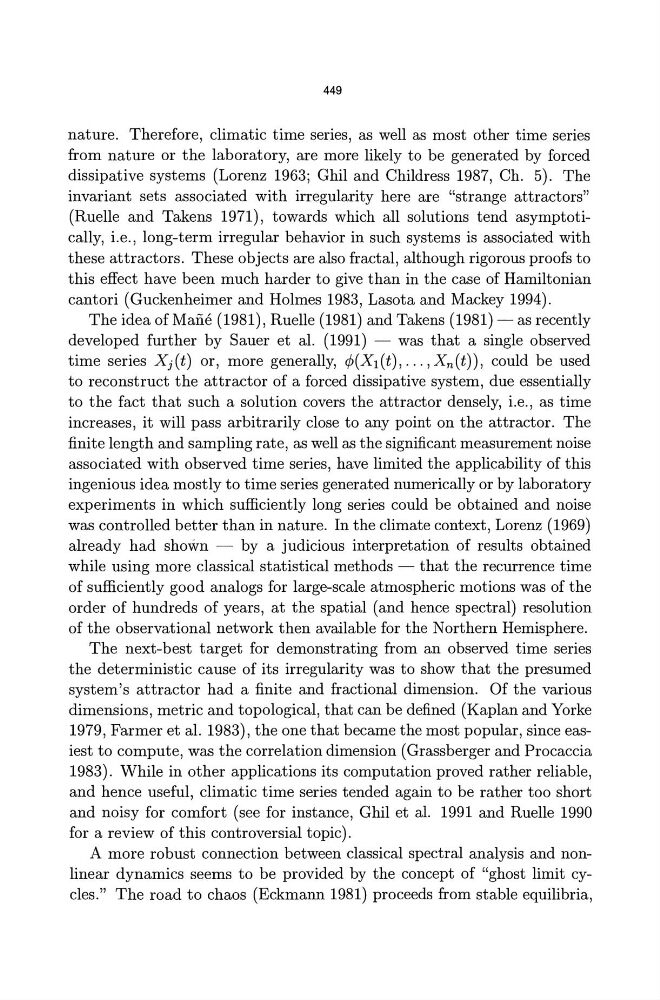
time series Xj (t) or, more generally, to reconstruct the attractor of a forced dissipative system, due essentially
to the fact that such a solution covers the attractor densely, i.e., as time
increases, it will pass arbitrarily close to any point on the attractor. The
finite length and sampling rate, as well as the significant measurement noise
associated with observed time series, have limited the applicability of this
ingenious idea mostly to time series generated numerically or by laboratory
experiments in which sufficiently long series could be obtained and noise
was controlled better than in nature. In the climate context, Lorenz (1969)
already had shown - by a judicious interpretation of results obtained
while using more classical statistical methods - that the recurrence time
of sufficiently good analogs for large-scale atmospheric motions was of the
order of hundreds of years, at the spatial (and hence spectral) resolution
of the observational network then available for the Northern Hemisphere.
The next-best target for demonstrating from an observed time series
the deterministic cause of its irregularity was to show that the presumed
system's attractor had a finite and fractional dimension. Of the various
dimensions, metric and topological, that can be defined (Kaplan and Yorke
1979, Farmer et al. 1983), the one that became the most popular, since easiest to compute, was the correlation dimension (Grassberger and Pro caccia
1983). While in other applications its computation proved rather reliable,
and hence useful, climatic time series tended again to be rather too short
and noisy for comfort (see for instance, Ghil et al. 1991 and Ruelle 1990
for a review of this controversial topic).
A more robust connection between classical spectral analysis and nonlinear dynamics seems to be provided by the concept of "ghost limit cycles." The road to chaos (Eckmann 1981) proceeds from stable equilibria,