

40
4 Stochastic Processes
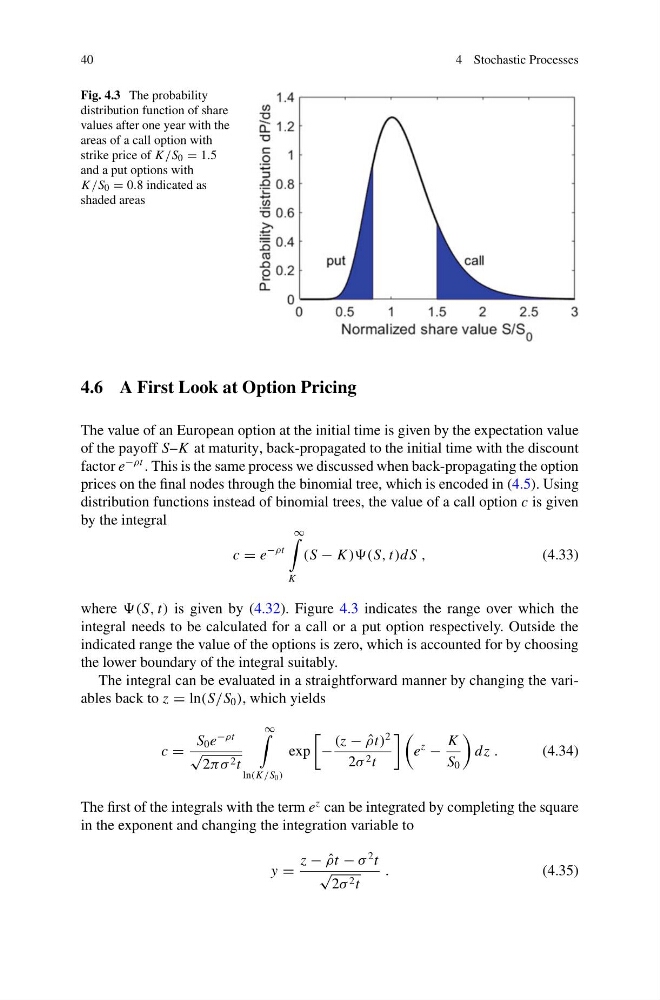
Fig. 4.3 The probability
distribution function of share
values after one year with the
areas of a call option with
strike price of K /S 0 = 1.5
and a put options with
K /S 0 = 0.8 indicated as
shaded areas
4.6 A First Look at Option Pricing
The value of an European option at the initial time is given by the expectation value
of the payoff S–K at maturity, back-propagated to the initial time with the discount
factor e
−ρt
. This is the same process we discussed when back-propagating the option
prices on the final nodes through the binomial tree, which is encoded in (4.5). Using
distribution functions instead of binomial trees, the value of a call option c is given
by the integral
c = e
−ρt
∞
K
(S − K ))(S, t)d S ,
(4.33)
where (S, t) is given by (4.32). Figure 4.3 indicates the range over which the
integral needs to be calculated for a call or a put option respectively. Outside the
indicated range the value of the options is zero, which is accounted for by choosing
the lower boundary of the integral suitably.
The integral can be evaluated in a straightforward manner by changing the variables back to z = ln(S/S 0 ), which yields
c =
S 0 e
−ρt
√
2πσ 2 t
∞
ln(K /S 0 )
exp
−
(z − ˆ
ρt)
2
2σ 2 t
e
z
−
K
S 0
dz .
(4.34)
The first of the integrals with the term e
z can be integrated by completing the square
in the exponent and changing the integration variable to
y =
z − ˆ
ρt − σ
2 t
√
2σ 2 t
.
(4.35)