

4.6 A First Look at Option Pricing
41
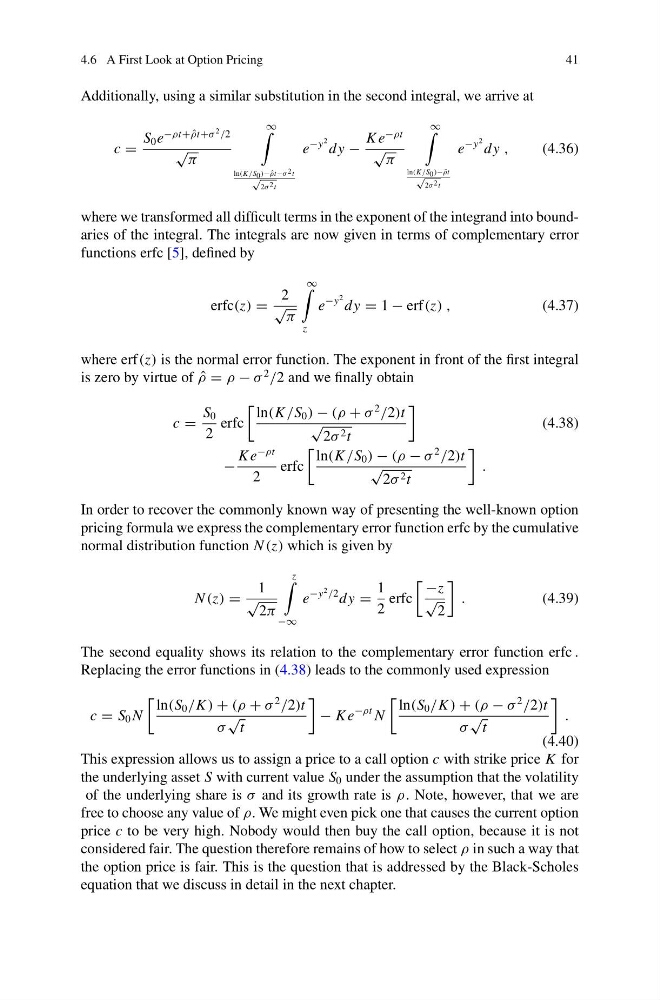
Additionally, using a similar substitution in the second integral, we arrive at
c =
S 0 e
−ρt+ ˆ
ρt+σ
2 /2
√
π
∞
ln(K /S 0 )− ˆ
ρt−σ 2 t
√
2σ 2 t
e
−y
2 dy −
K e
−ρt
√
π
∞
ln(K /S 0 )− ˆ
ρt
√
2σ 2 t
e
−y
2 dy ,
(4.36)
where we transformed all difficult terms in the exponent of the integrand into boundaries of the integral. The integrals are now given in terms of complementary error
functions erfc [5], defined by
erfc(z) =
2
√
π
∞
z
e
−y
2 dy = 1 − erf(z) ,
(4.37)
where erf(z) is the normal error function. The exponent in front of the first integral
is zero by virtue of ˆ
ρ = ρ − σ
2
/2 and we finally obtain
c =
S 0
2
erfc
ln(K /S 0 ) − (ρ + σ
2
/2)t
√
2σ 2 t
(4.38)
−
K e
−ρt
2
erfc
ln(K /S 0 ) − (ρ − σ
2
/2)t
√
2σ 2 t
.
In order to recover the commonly known way of presenting the well-known option
pricing formula we express the complementary error function erfc by the cumulative
normal distribution function N (z) which is given by
N (z) =
1
√
2π
z
−∞
e
−y
2 /2 dy =
1
2
erfc
−z
√
2
.
(4.39)
The second equality shows its relation to the complementary error function erfc .
Replacing the error functions in (4.38) leads to the commonly used expression
c = S 0 N
ln(S 0 /K ) + (ρ + σ
2
/2)t
σ
√
t
− K e
−ρt N
ln(S 0 /K ) + (ρ − σ
2
/2)t
σ
√
t
.
(4.40)
This expression allows us to assign a price to a call option c with strike price K for
the underlying asset S with current value S 0 under the assumption that the volatility
of the underlying share is σ and its growth rate is ρ. Note, however, that we are
free to choose any value of ρ. We might even pick one that causes the current option
price c to be very high. Nobody would then buy the call option, because it is not
considered fair. The question therefore remains of how to select ρ in such a way that
the option price is fair. This is the question that is addressed by the Black-Scholes
equation that we discuss in detail in the next chapter.