

242
13 Solutions for Selected Exercises
Exercise 5.1
Replacing the price for a call option c with that of a put option p in the steps from
(5.3) to (5.6) leads to the Black-Scholes equation for p.
Exercise 5.2
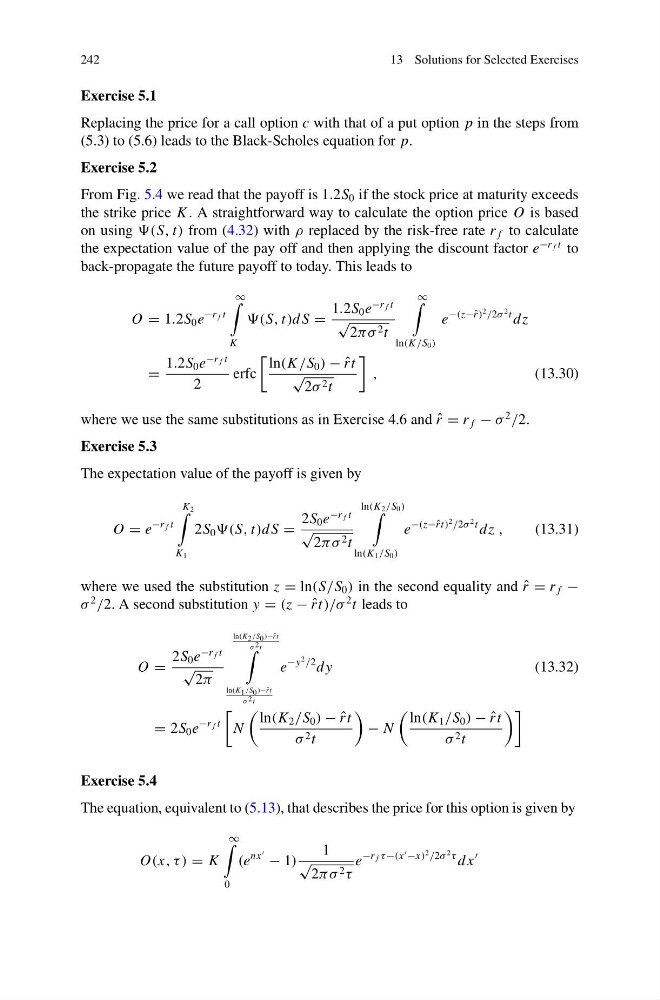
From Fig. 5.4 we read that the payoff is 1.2S 0 if the stock price at maturity exceeds
the strike price K . A straightforward way to calculate the option price O is based
on using (S, t) from (4.32) with ρ replaced by the risk-free rate r f to calculate
the expectation value of the pay off and then applying the discount factor e
−r f t to
back-propagate the future payoff to today. This leads to
O = 1.2S 0 e
−r f t
∞
K
(S, t)d S =
1.2S 0 e
−r f t
√
2πσ 2 t
∞
ln(K /S 0 )
e
−(z−ˆ r )
2 /2σ
2 t dz
=
1.2S 0 e
−r f t
2
erfc
ln(K /S 0 ) − ˆ
rt
√
2σ 2 t
,
(13.30)
where we use the same substitutions as in Exercise 4.6 and ˆ
r = r f − σ
2
/2.
Exercise 5.3
The expectation value of the payoff is given by
O = e
−r f t
K 2
K 1
2S 0 (S, t)d S =
2S 0 e
−r f t
√
2πσ 2 t
ln(K 2 /S 0 )
ln(K 1 /S 0 )
e
−(z−ˆ rt)
2 /2σ
2 t dz ,
(13.31)
where we used the substitution z = ln(S/S 0 ) in the second equality and ˆ
r = r f −
σ
2
/2. A second substitution y = (z − ˆ
rt)/σ
2 t leads to
O =
2S 0 e
−r f t
√
2π
ln(K 2 /S 0 )−ˆ rt
σ 2 t
ln(K 1 /S 0 )−ˆ rt
σ 2 t
e
−y
2 /2 dy
(13.32)
= 2S 0 e
−r f t
N
ln(K 2 /S 0 ) − ˆ
rt
σ 2 t
− N
ln(K 1 /S 0 ) − ˆ
rt
σ 2 t
Exercise 5.4
The equation, equivalent to (5.13), that describes the price for this option is given by
O(x, τ ) = K
∞
0
(e
nx
− 1)
1
√
2πσ 2 τ
e
−r f τ −(x
−x)
2 /2σ
2 τ dx