

8.6 Box-Jenkins
103
• Check whether the model describes the data adequately. If the fit is unsatisfactory,
possibly use more or different fit parameters.
• Once the model is established we can use it to forecast how the system evolves
into the future.
There are standardized software tools to perform all these steps. They use much
more sophisticated verification algorithms than those we used in this chapter. An
extensive list of available software is maintained on Wikipedia under the heading of
Comparison of statistical packages.
8.7 Forecasting
In the simplest case we can iterate the parsimonious model calculated in the earlier
section (and assuming all future unknown shocks to be equal to their expectation
value zero) to determine the forecast result. This works for both MA, AR, or ARMA
models. The error bars of the predicted values, however, are easiest to evaluate in
case we have an MA model. Therefore we first present a method that converts an
AR( p) or ARMA(p, q) model into an MA(∞) model such that we can later present
a unified method of forecasting the error bars. First, we introduce the lag operator ˆ
L
that is defined by the following relation on any sampled variable y i
ˆ
L y i = y i−1 ,
(8.26)
which simply changes a sample to the previous one. Repeated application of ˆ
L will
produce earlier samples such that ˆ
L
m y i = y i−m . This notation allows us to write the
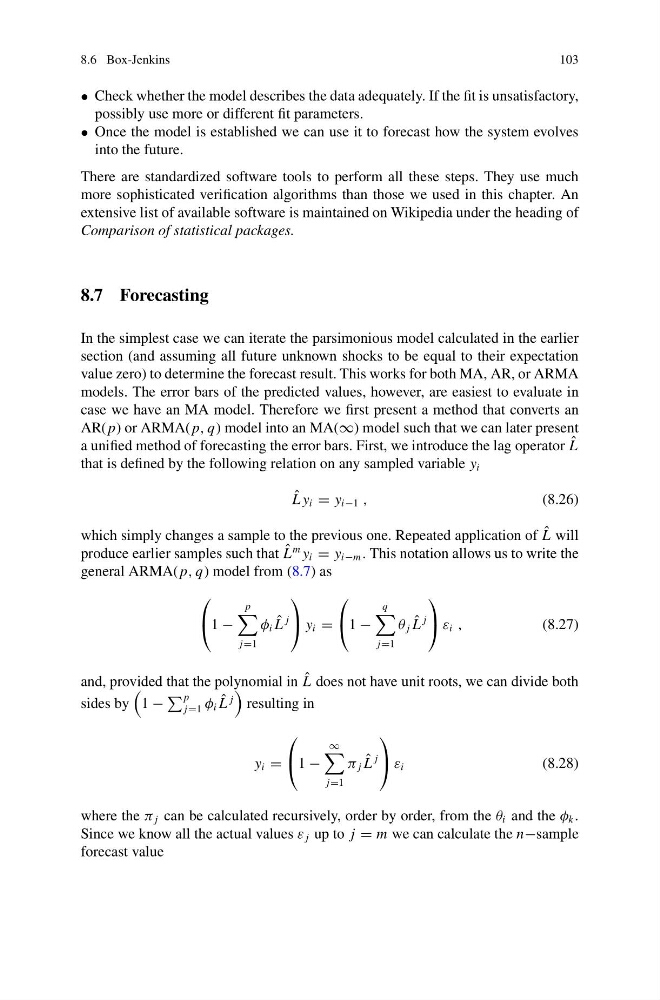
general ARMA( p, q) model from (8.7) as
⎛
⎝ 1 −
p
j=1
φ i ˆ
L
j
⎞
⎠ y i =
⎛
⎝ 1 −
q
j=1
θ j ˆ
L
j
⎞
⎠ ε i ,
(8.27)
and, provided that the polynomial in ˆ
L does not have unit roots, we can divide both
sides by
1 −
p
j=1 φ i ˆ
L
j
resulting in
y i =
⎛
⎝ 1 −
∞
j=1
π j ˆ
L
j
⎞
⎠ ε i
(8.28)
where the π j can be calculated recursively, order by order, from the θ i and the φ k .
Since we know all the actual values ε j up to j = m we can calculate the n−sample
forecast value