

8.6 COE and GOE
283
of the M×M Hermitian matrix, ¯
G M , as the set {g
i }, where i = 1, 2, . . . , M. The
OE distribution for the matrix ¯
G M satisfies the normalization condition
P
( ¯
G M )dd G M = C M
M(M+1)/2
∞
−∞
...
∞
−∞
dg
1 × . . . ×dg
M
×
1≤i
i |
M
j =1 [ 2 + (g
j − −g) 2 ] (M+1)/2
= 1.
(8.149)
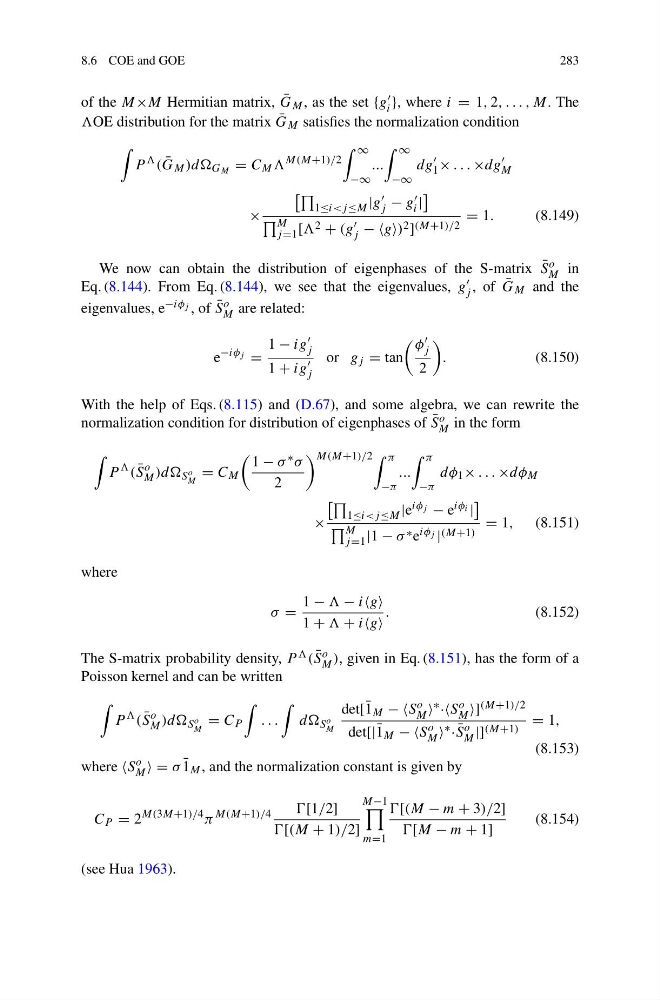
We now can obtain the distribution of eigenphases of the S-matrix ¯
S o
M in
Eq. (8.144). From Eq. (8.144), we see that the eigenvalues, g
j , of ¯
G M and the
eigenvalues, e −iφ j , of ¯
S o
M are related:
e
−iφ j =
1 − ig
j
1 + ig
j
or g j = tan
φ
j
2
.
(8.150)
With the help of Eqs. (8.115) and (D.67), and some algebra, we can rewrite the
normalization condition for distribution of eigenphases of ¯
S o
M in the form
P
( ¯
S
o
M )dd S o
M
= C M
1 − σ ∗ σ
2
M(M+1)/2 π
−π
...
π
−π
dφ 1 × . . . ×dφ M
×
1≤i
j =1 |1 − σ ∗ e iφ j | (M+1)
= 1, (8.151)
where
σ =
1 − − ig
1 + + ig
.
(8.152)
The S-matrix probability density, P ( ¯
S o
M ), given in Eq. (8.151), has the form of a
Poisson kernel and can be written
P
( ¯
S
o
M )dd S o
M
= C P
. . .
dd S o
M
det[ ¯
1 M − −S o
M ∗ ··S o
M ] (M+1)/2
det[| ¯
1 M − −S o
M ∗ · ¯
S o
M |] (M+1)
= 1,
(8.153)
where S o
M = σ ¯
1 M , and the normalization constant is given by
C P = 2
M(3M+1)/4 π
M(M+1)/4
[1/2]
[(M + 1)/2]
M−1
m=1
[(M − m + 3)/2]
[M − m + 1]
(8.154)
(see Hua 1963).