

6.4 Eigenvalue Statistics: Gaussian Orthogonal Ensemble
179
neighbor spacing distribution for a sequence of two eigenvalues obtained from
an ensemble of 2 × 2 random real symmetric matrices (Wigner 1957b). The
distribution function derived by Wigner, now called the Wigner distribution, is
surprisingly robust. It describes very well, but not exactly, the nearest neighbor
spacing distribution for a sequence of N eigenvalues obtained from an N×N real
symmetric matrix.
The nearest neighbor spacing distribution is a much more complicated object
than the eigenvalue number density or the 3 -statistic derived in the previous two
sections. Whereas the eigenvalue number density depends only on the one-body
cluster function, and the 3 -statistic depends only on one-body and two-body
cluster functions, the nearest neighbor spacing distribution depends on all the
cluster functions. Thus, for an N × N random Hermitian matrix, it is not possible
to obtain an analytic expression for the eigenvalue nearest neighbor spacing
distribution. It is possible, however, to obtain upper and lower bounds for it and show
that the result obtained by Wigner for 2×2 matrices gives a very good approximation
to the eigenvalue nearest neighbor spacing distribution for N × N matrices.
In this section, we will first obtain the eigenvalue nearest neighbor spacing
distribution for 2 × 2 random matrices from the Gaussian orthogonal ensemble
(GOE), and then we will give a general definition of the eigenvalue nearest neighbor
spacing distribution for N eigenvalues and discuss its limiting behavior as N → ∞.
Eigenvalue Spacing Distribution (N = 2)
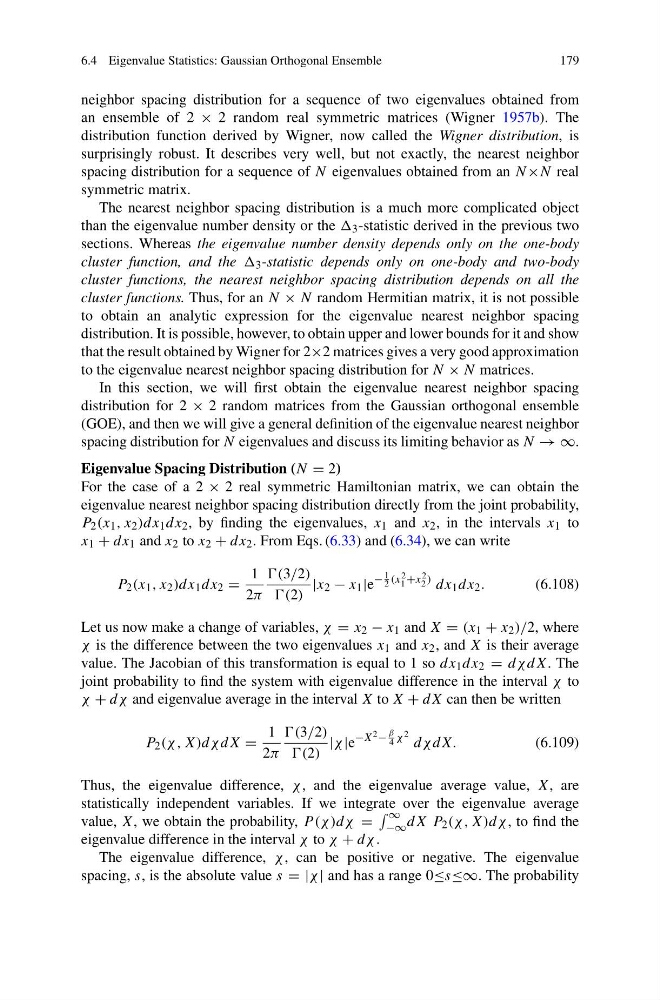
For the case of a 2 × 2 real symmetric Hamiltonian matrix, we can obtain the
eigenvalue nearest neighbor spacing distribution directly from the joint probability,
P 2 (x 1 , x 2 )dx 1 dx 2 , by finding the eigenvalues, x 1 and x 2 , in the intervals x 1 to
x 1 + dx 1 and x 2 to x 2 + dx 2 . From Eqs. (6.33) and (6.34), we can write
P 2 (x 1 , x 2 )dx 1 dx 2 =
1
2π
(3/2)
(2)
|x 2 − x 1 |e
−
1
2 (x 2
1 +x 2
2 ) dx 1 dx 2 .
(6.108)
Let us now make a change of variables, χ = x 2 − x 1 and X = (x 1 + x 2 )/2, where
χ is the difference between the two eigenvalues x 1 and x 2 , and X is their average
value. The Jacobian of this transformation is equal to 1 so dx 1 dx 2 = dχdX. The
joint probability to find the system with eigenvalue difference in the interval χ to
χ + dχ and eigenvalue average in the interval X to X + dX can then be written
P 2 (χ , X)dχ dX =
1
2π
(3/2)
(2)
|χ |e
−X 2 −
β
4 χ 2 dχdX.
(6.109)
Thus, the eigenvalue difference, χ , and the eigenvalue average value, X, are
statistically independent variables. If we integrate over the eigenvalue average
value, X, we obtain the probability, P (χ)dχ =
∞
−∞ dX P 2 (χ , X)dχ , to find the
eigenvalue difference in the interval χ to χ + dχ.
The eigenvalue difference, χ , can be positive or negative. The eigenvalue
spacing, s, is the absolute value s = |χ | and has a range 0≤s≤∞. The probability