

E.1 Stochastic Dynamics
173
equation well defined, in Itô’s calculus. That’s why it’s also known as “Itô-Langevin
Equation”.
E.1.7.5 Stratonovich’s Calculus
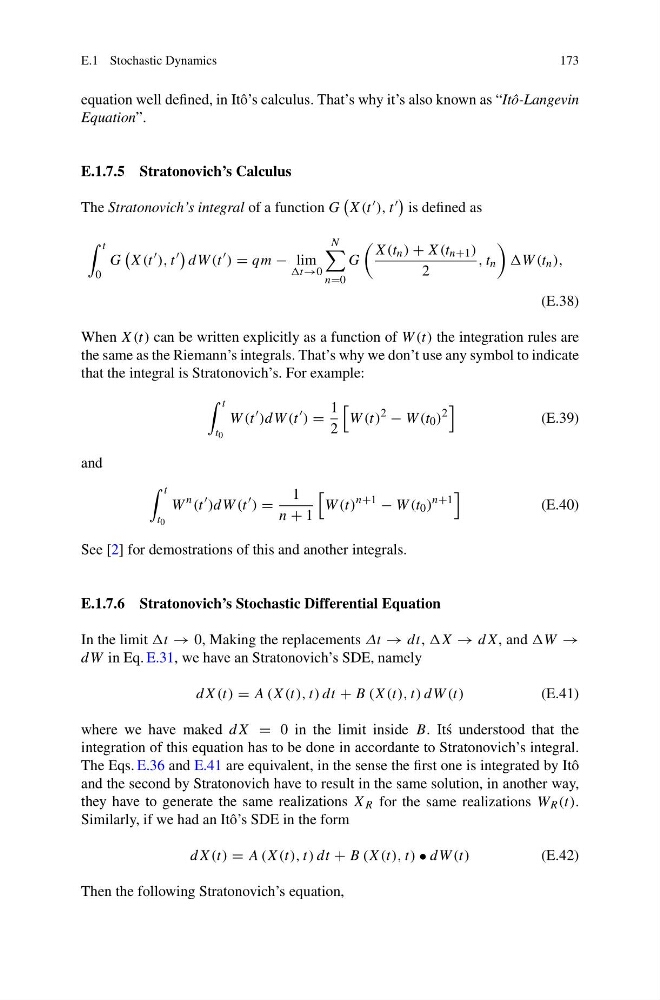
The Stratonovich’s integral of a function G
X(t ), t
is defined as
t
0
G
X(t
), t
dW (t
) = qm − lim
t→0
N
n=0
G
X(t n ) + X(t n+1 )
2
, t n
(t n ),
(E.38)
When X(t) can be written explicitly as a function of W (t) the integration rules are
the same as the Riemann’s integrals. That’s why we don’t use any symbol to indicate
that the integral is Stratonovich’s. For example:
t
t 0
W (t
)dW (t
) =
1
2
W (t)
2
− W (t 0 )
2
(E.39)
and
t
t 0
W
n (t
)dW (t
) =
1
n + 1
W (t)
n+1
− W (t 0 )
n+1
(E.40)
See [2] for demostrations of this and another integrals.
E.1.7.6 Stratonovich’s Stochastic Differential Equation
In the limit t → 0, Making the replacements Δt → dt, X → dX, and W →
dW in Eq. E.31, we have an Stratonovich’s SDE, namely
dX(t) = A (X(t), t) dt + B (X(t), t) dW (t)
(E.41)
where we have maked dX = 0 in the limit inside B. It´ s understood that the
integration of this equation has to be done in accordante to Stratonovich’s integral.
The Eqs. E.36 and E.41 are equivalent, in the sense the first one is integrated by Itô
and the second by Stratonovich have to result in the same solution, in another way,
they have to generate the same realizations X R for the same realizations W R (t).
Similarly, if we had an Itô’s SDE in the form
dX(t) = A (X(t), t) dt + B (X(t), t) • dW (t)
(E.42)
Then the following Stratonovich’s equation,