

172
Appendix E
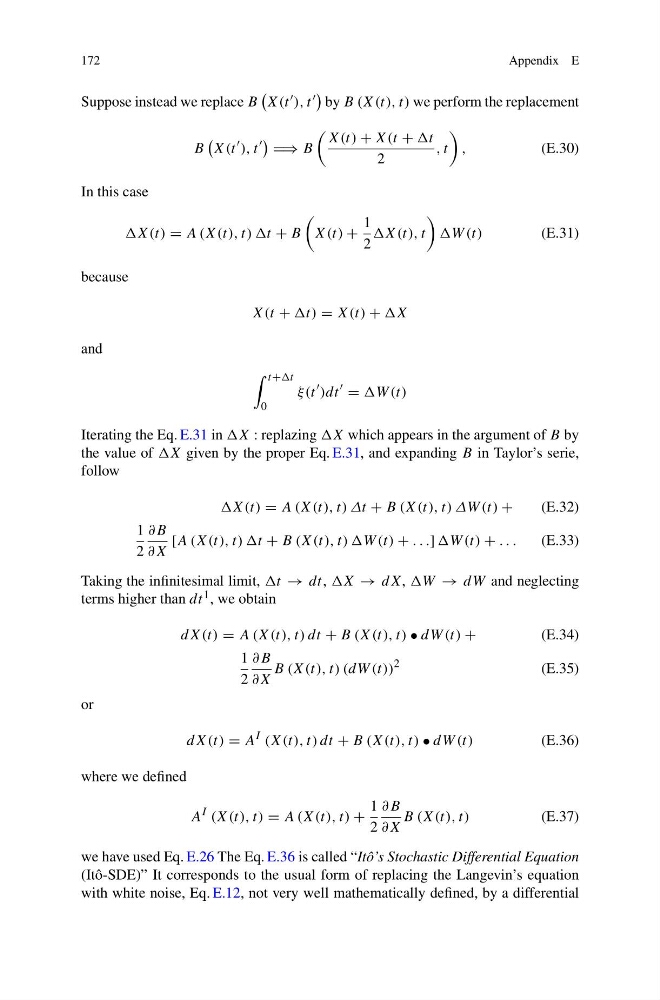
Suppose instead we replace B
X(t ), t
by B (X(t), t) we perform the replacement
B
X(t
), t
⇒ B
X(t) + X(t + t
2
, t
,
(E.30)
In this case
= A (X(t), t) t + B
X(t) +
1
2
X(t), t
(t)
(E.31)
because
X(t + t) = X(t) + X
and
t+t
0
ξ(t
)dt
= W (t)
Iterating the Eq. E.31 in X : replazing X which appears in the argument of B by
the value of X given by the proper Eq. E.31, and expanding B in Taylor’s serie,
follow
= A (X(t), t) Δt + B (X(t), t) ΔW (t) +
(E.32)
1
2
∂B
∂X
[A (X(t), t) t + B (X(t), t) (t) + . . .] W (t) + . . .
(E.33)
Taking the infinitesimal limit, t → dt, X → dX, W → dW and neglecting
terms higher than dt 1 , we obtain
dX(t) = A (X(t), t) dt + B (X(t), t) • dW (t) +
(E.34)
1
2
∂B
∂X
B (X(t), t) (dW (t))
2
(E.35)
or
dX(t) = A
I (X(t), t) dt + B (X(t), t) • dW (t)
(E.36)
where we defined
A
I (X(t), t) = A (X(t), t) +
1
2
∂B
∂X
B (X(t), t)
(E.37)
we have used Eq. E.26 The Eq. E.36 is called “Itô’s Stochastic Differential Equation
(Itô-SDE)” It corresponds to the usual form of replacing the Langevin’s equation
with white noise, Eq. E.12, not very well mathematically defined, by a differential