

174
Appendix E
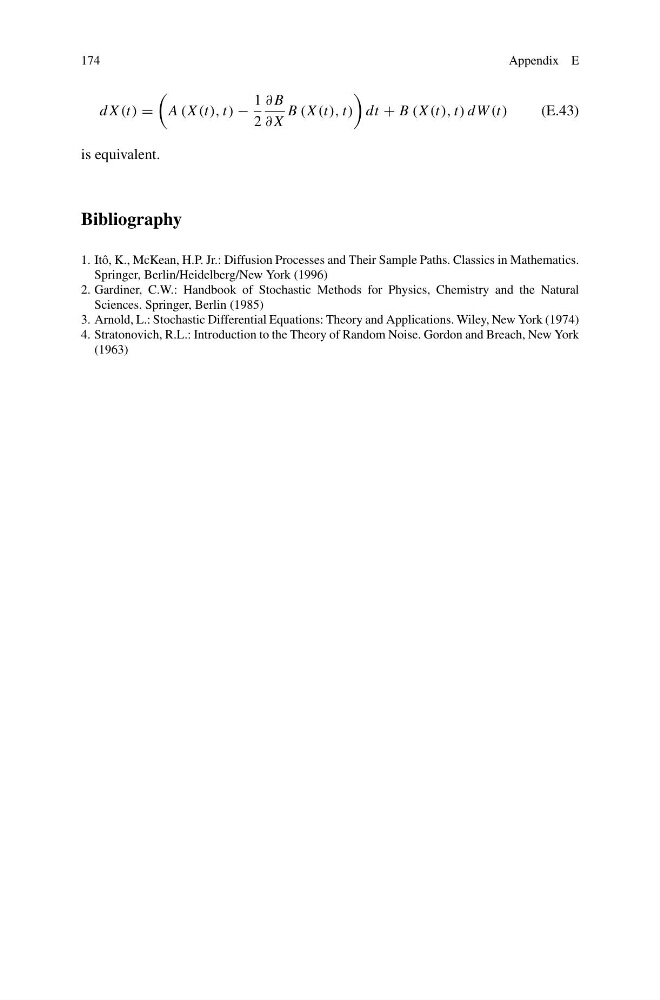
dX(t) =
A (X(t), t) −
1
2
∂B
∂X
B (X(t), t)
dt + B (X(t), t) dW (t)
(E.43)
is equivalent.
Bibliography
1. Itô, K., McKean, H.P. Jr.: Diffusion Processes and Their Sample Paths. Classics in Mathematics.
Springer, Berlin/Heidelberg/New York (1996)
2. Gardiner, C.W.: Handbook of Stochastic Methods for Physics, Chemistry and the Natural
Sciences. Springer, Berlin (1985)
3. Arnold, L.: Stochastic Differential Equations: Theory and Applications. Wiley, New York (1974)
4. Stratonovich, R.L.: Introduction to the Theory of Random Noise. Gordon and Breach, New York
(1963)