

43
data itself but the weighted ones. The simplest case is to assign smaller weights for observations from the past periods than from the current period (not far from the present time
point). In the literature one can find different modifications of the classical measures of
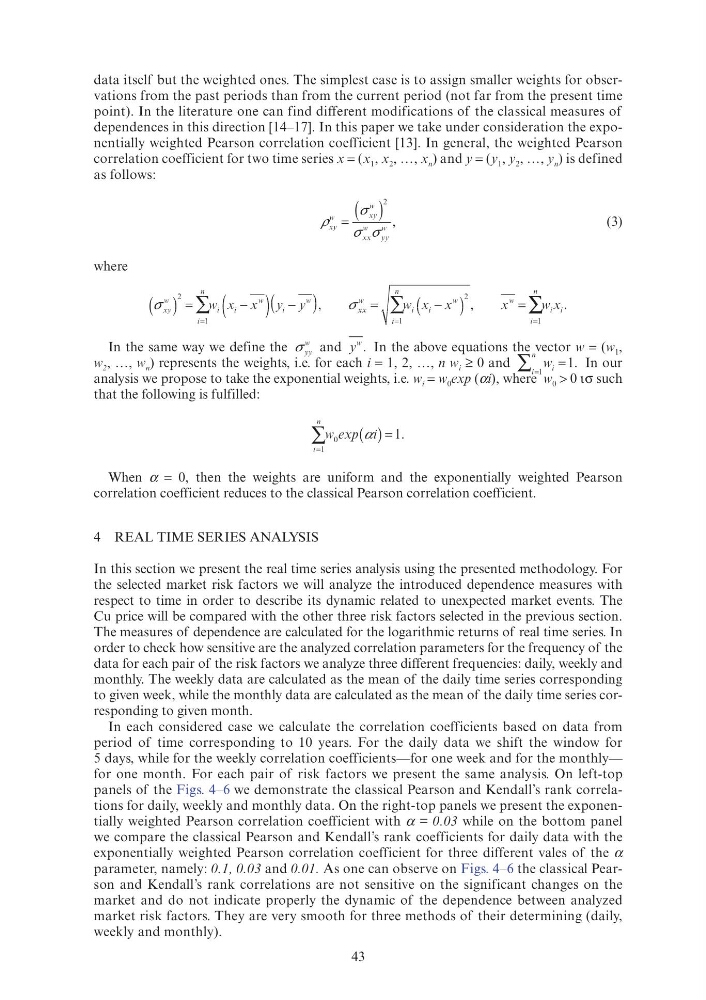
dependences in this direction [14–17]. In this paper we take under consideration the exponentially weighted Pearson correlation coefficient [13]. In general, the weighted Pearson
correlation coefficient for two time series x = (x 1 , x 2 , …, x n ) and y = (y 1 , y 2 , …, y n ) is defined
as follows:
ρ
σ
σ σ
xy
w
ρ
xy
w
σ
xx
σ σ
w
σ yy
w
σ
=
( )
2
,
(3)
where
i
n
i
n
i
w
i
n
w
x
( )
σ xy
σ σ
w
( )
(
)
i
(
)
w
x x
i
=
(
)
=
=
∑
xx
∑ i
∑
∑
σ
w
w w
σ xx
w
( )
i
w
σ
(
)
i
w
y y
2
1
1
i
( )
=
i
2
1
,
i
w
)
i
x
i
w w
σ xx
∑ ∑ w x
∑ ∑ ∑ i i
x .
In the same way we define the σ yy
w and y
w . In the above equations the vector w = (w 1 ,
w 2 , …, w n ) represents the weights, i.e. for each i = 1, 2, …, n w i ≥ 0 and
w i
i
n
=
=
∑
1
1
. In our
analysis we propose to take the exponential weights, i.e. w i = w 0 exp (αi), where w 0 > 0 ισ such
that the following is fulfilled:
i
n
w exp
=
∑
( )
i =
1
0
1
i i
.
When α = 0, then the weights are uniform and the exponentially weighted Pearson
correlation coefficient reduces to the classical Pearson correlation coefficient.
4 REAL TIME SERIES ANALYSIS
In this section we present the real time series analysis using the presented methodology. For
the selected market risk factors we will analyze the introduced dependence measures with
respect to time in order to describe its dynamic related to unexpected market events. The
Cu price will be compared with the other three risk factors selected in the previous section.
The measures of dependence are calculated for the logarithmic returns of real time series. In
order to check how sensitive are the analyzed correlation parameters for the frequency of the
data for each pair of the risk factors we analyze three different frequencies: daily, weekly and
monthly. The weekly data are calculated as the mean of the daily time series corresponding
to given week, while the monthly data are calculated as the mean of the daily time series corresponding to given month.
In each considered case we calculate the correlation coefficients based on data from
period of time corresponding to 10 years. For the daily data we shift the window for
5 days, while for the weekly correlation coefficients—for one week and for the monthly—
for one month. For each pair of risk factors we present the same analysis. On left-top
panels of the Figs. 4–6 we demonstrate the classical Pearson and Kendall’s rank correlations for daily, weekly and monthly data. On the right-top panels we present the exponentially weighted Pearson correlation coefficient with α = 0.03 while on the bottom panel
we compare the classical Pearson and Kendall’s rank coefficients for daily data with the
exponentially weighted Pearson correlation coefficient for three different vales of the α
parameter, namely: 0.1, 0.03 and 0.01. As one can observe on Figs. 4–6 the classical Pearson and Kendall’s rank correlations are not sensitive on the significant changes on the
market and do not indicate properly the dynamic of the dependence between analyzed
market risk factors. They are very smooth for three methods of their determining (daily,
weekly and monthly).