

418
E. M. Tirado and D. Quagliarella
Conversely, the Value-at-Risk is not a coherent measure since it does not respect
the sub-additivity property.
13.4 Robust Optimization Problem Using Risk Functions
Risk measures, likewise expectations and variance, are unknown parameters of a
statistical model (estimands), which can be only approximated using estimators
and finite samples of data. Consequently, the robust optimization problem has to
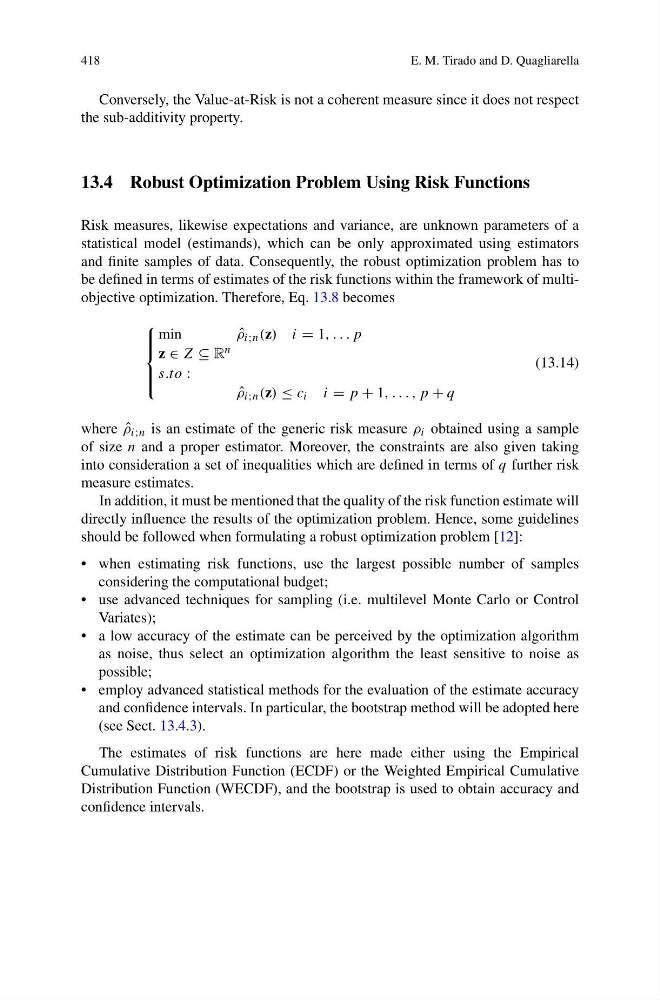
be defined in terms of estimates of the risk functions within the framework of multiobjective optimization. Therefore, Eq. 13.8 becomes
⎧
⎪ ⎪ ⎨
⎪ ⎪ ⎩
min
ˆ
ρ i;n (z) i = 1, . . . p
z ∈ Z ⊆ R n
s.to :
ˆ
ρ i;n (z) ≤ c i i = p + 1, . . . , p + q
(13.14)
where ˆ
ρ i;n is an estimate of the generic risk measure ρ i obtained using a sample
of size n and a proper estimator. Moreover, the constraints are also given taking
into consideration a set of inequalities which are defined in terms of q further risk
measure estimates.
In addition, it must be mentioned that the quality of the risk function estimate will
directly influence the results of the optimization problem. Hence, some guidelines
should be followed when formulating a robust optimization problem [12]:
• when estimating risk functions, use the largest possible number of samples
considering the computational budget;
• use advanced techniques for sampling (i.e. multilevel Monte Carlo or Control
Variates);
• a low accuracy of the estimate can be perceived by the optimization algorithm
as noise, thus select an optimization algorithm the least sensitive to noise as
possible;
• employ advanced statistical methods for the evaluation of the estimate accuracy
and confidence intervals. In particular, the bootstrap method will be adopted here
(see Sect. 13.4.3).
The estimates of risk functions are here made either using the Empirical
Cumulative Distribution Function (ECDF) or the Weighted Empirical Cumulative
Distribution Function (WECDF), and the bootstrap is used to obtain accuracy and
confidence intervals.