

460
Solutions
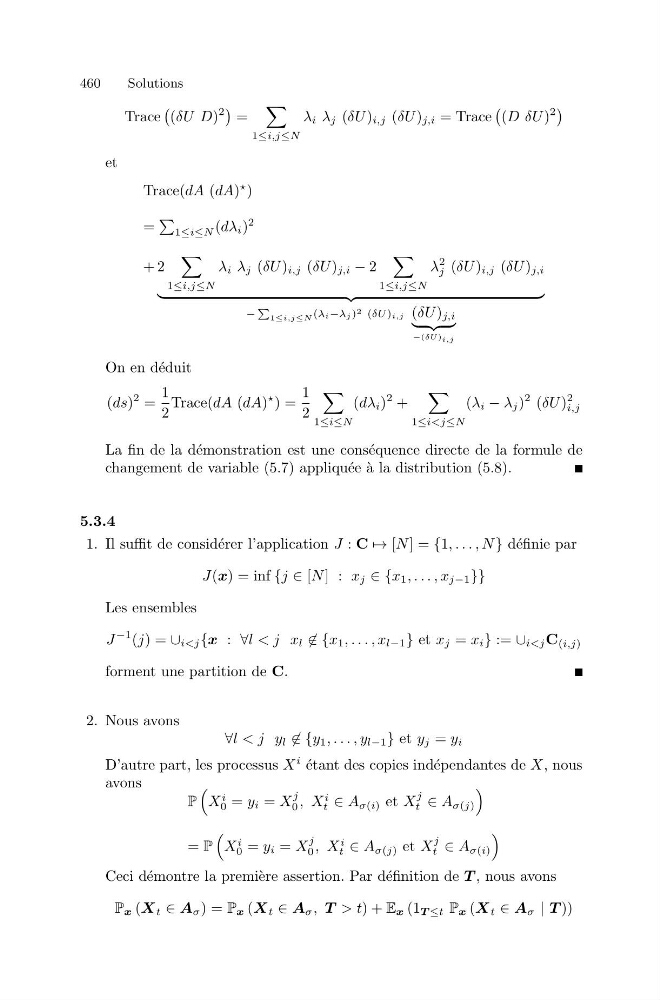
Trace
(δU D)
2
=
1≤i,j≤N
λ i λ j (δU ) i,j (δU ) j,i = Trace
(D δU)
2
et
Trace(dA (dA)
)
=
1≤i≤N (dλ i )
2
+ 2
1≤i,j≤N
λ i λ j (δU ) i,j (δU ) j,i − 2
1≤i,j≤N
λ
2
j (δU ) i,j (δU ) j,i
−
1≤i,j≤N (λi−λj ) 2 (δU )i,j (δU ) j,i
−(δU ) i,j
On en d´ eduit
(ds)
2 =
1
2
Trace(dA (dA)
) =
1
2
1≤i≤N
(dλ i )
2 +
1≤i
2 (δU )
2
i,j
La fin de la d´ emonstration est une cons´ equence directe de la formule de
changement de variable (5.7) appliqu´ ee `
a la distribution (5.8).
5.3.4
1. Il suffit de consid´ erer l’application J : C → [N ] = {1, . . . , N} d´ efinie par
J(x) = inf {j ∈ [N ] : x j ∈ {x 1 , . . . , x j−1 }}
Les ensembles
J
−1 (j) = ∪ i
2. Nous avons
∀l < j y l ∈ {y 1 , . . . , y l−1 } et y j = y i
D’autre part, les processus X
i ´ etant des copies ind´ ependantes de X, nous
avons
P
X
i
0 = y i = X
j
0 , X
i
t ∈ A σ(i) et X
j
t ∈ A σ(j)
= P
X
i
0 = y i = X
j
0 , X
i
t ∈ A σ(j) et X
j
t ∈ A σ(i)
Ceci d´ emontre la premi` ere assertion. Par d´ efinition de T , nous avons
P x (X t ∈ A σ ) = P x (X t ∈ A σ , T > t) + E x (1 T ≤t P x (X t ∈ A σ | T ))