

118
5 Du temps discret au temps continu
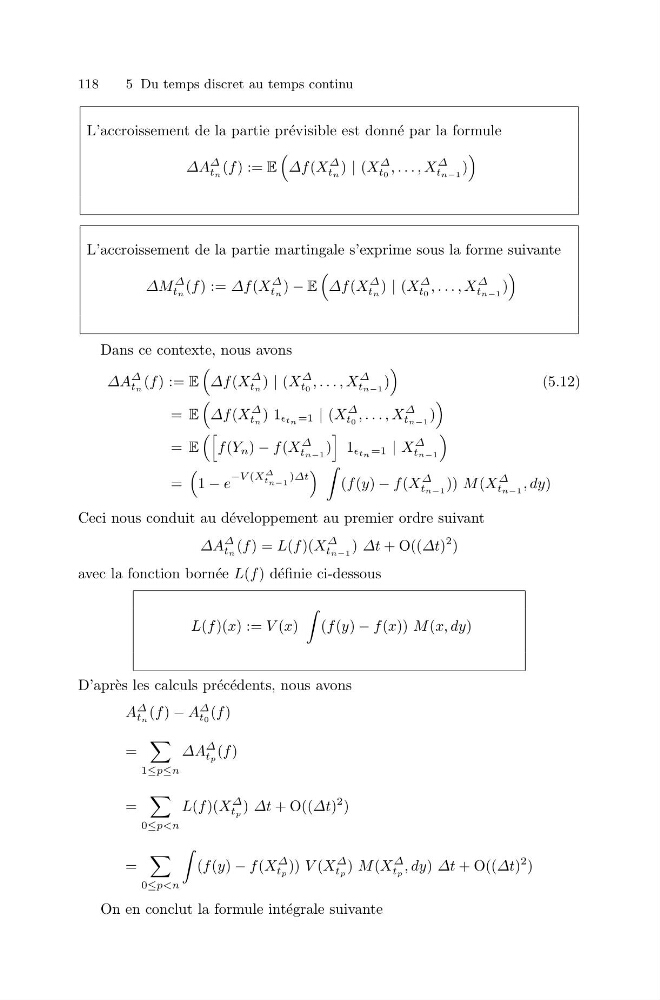
L’accroissement de la partie pr´ evisible est donn´ e par la formule
ΔA
Δ
tn (f ) := E
Δf (X
Δ
tn ) | (X
Δ
t0 , . . . , X
Δ
tn−1 )
L’accroissement de la partie martingale s’exprime sous la forme suivante
ΔM
Δ
tn (f ) := Δf (X
Δ
tn ) − E
Δf (X
Δ
tn ) | (X
Δ
t0 , . . . , X
Δ
tn−1 )
Dans ce contexte, nous avons
ΔA
Δ
tn (f ) := E
Δf (X
Δ
tn ) | (X
Δ
t0 , . . . , X
Δ
tn−1 )
(5.12)
= E
Δf (X
Δ
tn ) 1 n =1 | (X
Δ
t0 , . . . , X
Δ
tn−1 )
= E
f (Y n ) − f (X
Δ
tn−1 )
1 t n =1 | X
Δ
tn−1
=
1 − e
−V (X
Δ
t n−1
)Δt
(f (y) − f (X
Δ
tn−1 )) M (X
Δ
tn−1 , dy)
Ceci nous conduit au d´ eveloppement au premier ordre suivant
ΔA
Δ
tn (f ) = L(f )(X
Δ
tn−1 ) Δt + O((Δt)
2 )
avec la fonction born´ ee L(f ) d´ efinie ci-dessous
L(f )(x) := V (x)
(f (y) − f (x)) M (x, dy)
D’apr` es les calculs pr´ ec´ edents, nous avons
A
Δ
tn (f ) − A
Δ
t0 (f )
=
1≤p≤n
ΔA
Δ
tp (f )
=
0≤p
Δ
tp ) Δt + O((Δt)
2 )
=
0≤p
Δ
tp )) V (X
Δ
tp ) M (X
Δ
tp , dy) Δt + O((Δt)
2 )
On en conclut la formule int´ egrale suivante