

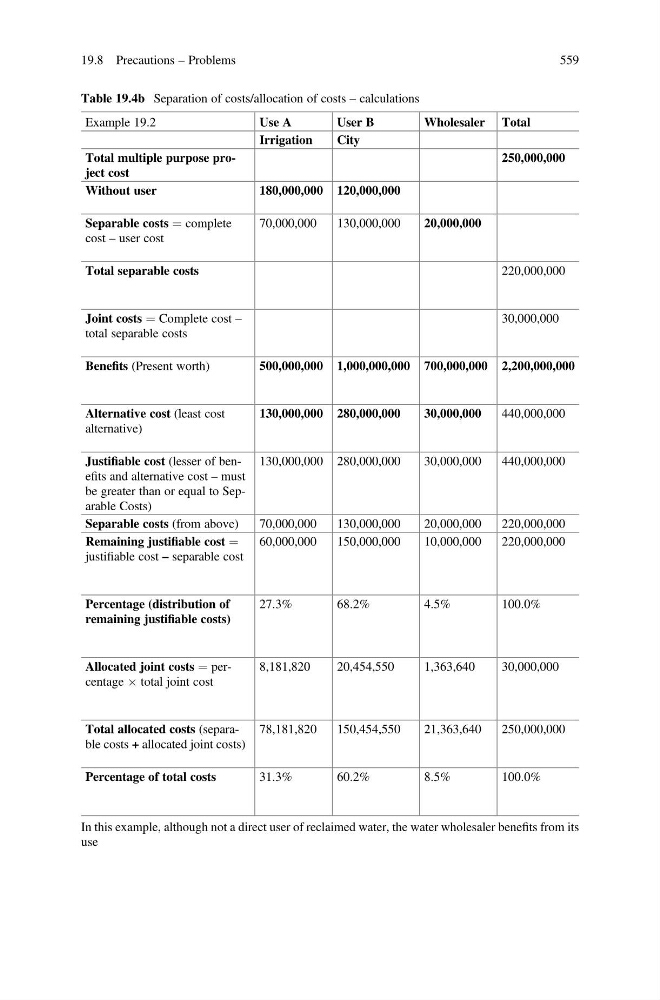
Table 19.4b Separation of costs/allocation of costs – calculations
Example 19.2
Use A
User B
Wholesaler Total
Irrigation
City
Total multiple purpose project cost
250,000,000
Without user
180,000,000 120,000,000
Separable costs ¼ complete
cost – user cost
70,000,000
130,000,000
20,000,000
Total separable costs
220,000,000
Joint costs ¼ Complete cost –
total separable costs
30,000,000
Benefits (Present worth)
500,000,000 1,000,000,000 700,000,000 2,200,000,000
Alternative cost (least cost
alternative)
130,000,000 280,000,000
30,000,000
440,000,000
Justifiable cost (lesser of benefits and alternative cost – must
be greater than or equal to Separable Costs)
130,000,000 280,000,000
30,000,000
440,000,000
Separable costs (from above)
70,000,000
130,000,000
20,000,000
220,000,000
Remaining justifiable cost ¼
justifiable cost – separable cost
60,000,000
150,000,000
10,000,000
220,000,000
Percentage (distribution of
remaining justifiable costs)
27.3%
68.2%
4.5%
100.0%
Allocated joint costs ¼ percentage  total joint cost
8,181,820
20,454,550
1,363,640
30,000,000
Total allocated costs (separable costs + allocated joint costs)
78,181,820
150,454,550
21,363,640
250,000,000
Percentage of total costs
31.3%
60.2%
8.5%
100.0%
In this example, although not a direct user of reclaimed water, the water wholesaler benefits from its
use
19.8 Precautions – Problems
559