

7. Estimation ponctuelle 149
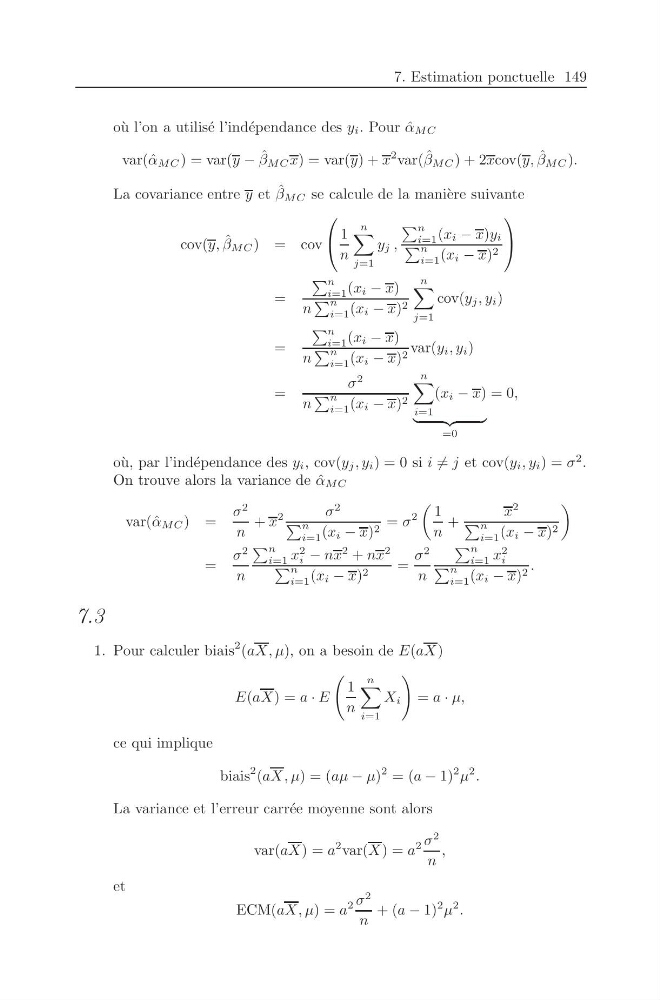
o` u l’on a utilis´ e l’ind´ ependance des y i . Pour ˆ
α MC
var(ˆ α MC ) = var(y − ˆ
β MC x) = var(y) + x
2 var( ˆ
β MC ) + 2xcov(y, ˆ
β MC ).
La covariance entre y et ˆ
β MC se calcule de la mani` ere suivante
cov(y, ˆ
β MC ) = cov
1
n
n
j=1
y j ,
n
i=1 (x i − x)y i
n
i=1 (x i − x) 2
=
n
i=1 (x i − x)
n
n
i=1 (x i − x) 2
n
j=1
cov(y j , y i )
=
n
i=1 (x i − x)
n
n
i=1 (x i − x) 2 var(y i , y i )
=
σ
2
n
n
i=1 (x i − x) 2
n
i=1
(x i − x)
=0
= 0,
o` u, par l’ind´ ependance des y i , cov(y j , y i ) = 0 si i = j et cov(y i , y i ) = σ
2 .
On trouve alors la variance de ˆ
α MC
var(ˆ α MC ) =
σ
2
n
+ x
2
σ
2
n
i=1 (x i − x) 2 = σ
2
1
n
+
x
2
n
i=1 (x i − x) 2
=
σ
2
n
n
i=1 x
2
i − nx
2 + nx
2
n
i=1 (x i − x) 2
=
σ
2
n
n
i=1 x
2
i
n
i=1 (x i − x) 2 .
7.3
1. Pour calculer biais
2 (aX, µ), on a besoin de E(aX)
E(aX) = a · E
1
n
n
i=1
X i
= a · µ,
ce qui implique
biais
2 (aX, µ) = (aµ − µ)
2 = (a − 1)
2 µ
2 .
La variance et l’erreur carr´ ee moyenne sont alors
var(aX) = a
2 var(X) = a
2 σ
2
n
,
et
ECM(aX, µ) = a
2 σ
2
n
+ (a − 1)
2 µ
2 .