

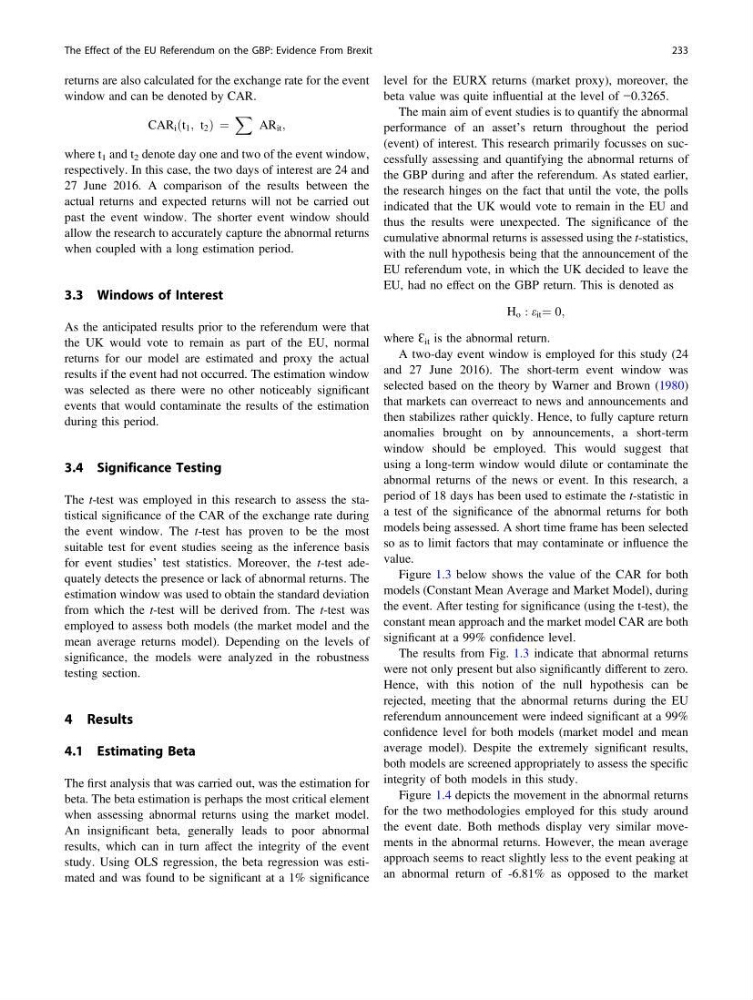
returns are also calculated for the exchange rate for the event
window and can be denoted by CAR.
CAR i t 1 ; t 2
ð
Þ ¼
X
AR it ;
where t 1 and t 2 denote day one and two of the event window,
respectively. In this case, the two days of interest are 24 and
27 June 2016. A comparison of the results between the
actual returns and expected returns will not be carried out
past the event window. The shorter event window should
allow the research to accurately capture the abnormal returns
when coupled with a long estimation period.
3.3 Windows of Interest
As the anticipated results prior to the referendum were that
the UK would vote to remain as part of the EU, normal
returns for our model are estimated and proxy the actual
results if the event had not occurred. The estimation window
was selected as there were no other noticeably significant
events that would contaminate the results of the estimation
during this period.
3.4 Significance Testing
The t-test was employed in this research to assess the statistical significance of the CAR of the exchange rate during
the event window. The t-test has proven to be the most
suitable test for event studies seeing as the inference basis
for event studies’ test statistics. Moreover, the t-test adequately detects the presence or lack of abnormal returns. The
estimation window was used to obtain the standard deviation
from which the t-test will be derived from. The t-test was
employed to assess both models (the market model and the
mean average returns model). Depending on the levels of
significance, the models were analyzed in the robustness
testing section.
4 Results
4.1 Estimating Beta
The first analysis that was carried out, was the estimation for
beta. The beta estimation is perhaps the most critical element
when assessing abnormal returns using the market model.
An insignificant beta, generally leads to poor abnormal
results, which can in turn affect the integrity of the event
study. Using OLS regression, the beta regression was estimated and was found to be significant at a 1% significance
level for the EURX returns (market proxy), moreover, the
beta value was quite influential at the level of −0.3265.
The main aim of event studies is to quantify the abnormal
performance of an asset’s return throughout the period
(event) of interest. This research primarily focusses on successfully assessing and quantifying the abnormal returns of
the GBP during and after the referendum. As stated earlier,
the research hinges on the fact that until the vote, the polls
indicated that the UK would vote to remain in the EU and
thus the results were unexpected. The significance of the
cumulative abnormal returns is assessed using the t-statistics,
with the null hypothesis being that the announcement of the
EU referendum vote, in which the UK decided to leave the
EU, had no effect on the GBP return. This is denoted as
H o : e it ¼ 0;
where Ɛ it is the abnormal return.
A two-day event window is employed for this study (24
and 27 June 2016). The short-term event window was
selected based on the theory by Warner and Brown (1980)
that markets can overreact to news and announcements and
then stabilizes rather quickly. Hence, to fully capture return
anomalies brought on by announcements, a short-term
window should be employed. This would suggest that
using a long-term window would dilute or contaminate the
abnormal returns of the news or event. In this research, a
period of 18 days has been used to estimate the t-statistic in
a test of the significance of the abnormal returns for both
models being assessed. A short time frame has been selected
so as to limit factors that may contaminate or influence the
value.
Figure 1.3 below shows the value of the CAR for both
models (Constant Mean Average and Market Model), during
the event. After testing for significance (using the t-test), the
constant mean approach and the market model CAR are both
significant at a 99% confidence level.
The results from Fig. 1.3 indicate that abnormal returns
were not only present but also significantly different to zero.
Hence, with this notion of the null hypothesis can be
rejected, meeting that the abnormal returns during the EU
referendum announcement were indeed significant at a 99%
confidence level for both models (market model and mean
average model). Despite the extremely significant results,
both models are screened appropriately to assess the specific
integrity of both models in this study.
Figure 1.4 depicts the movement in the abnormal returns
for the two methodologies employed for this study around
the event date. Both methods display very similar movements in the abnormal returns. However, the mean average
approach seems to react slightly less to the event peaking at
an abnormal return of -6.81% as opposed to the market
The Effect of the EU Referendum on the GBP: Evidence From Brexit
233