

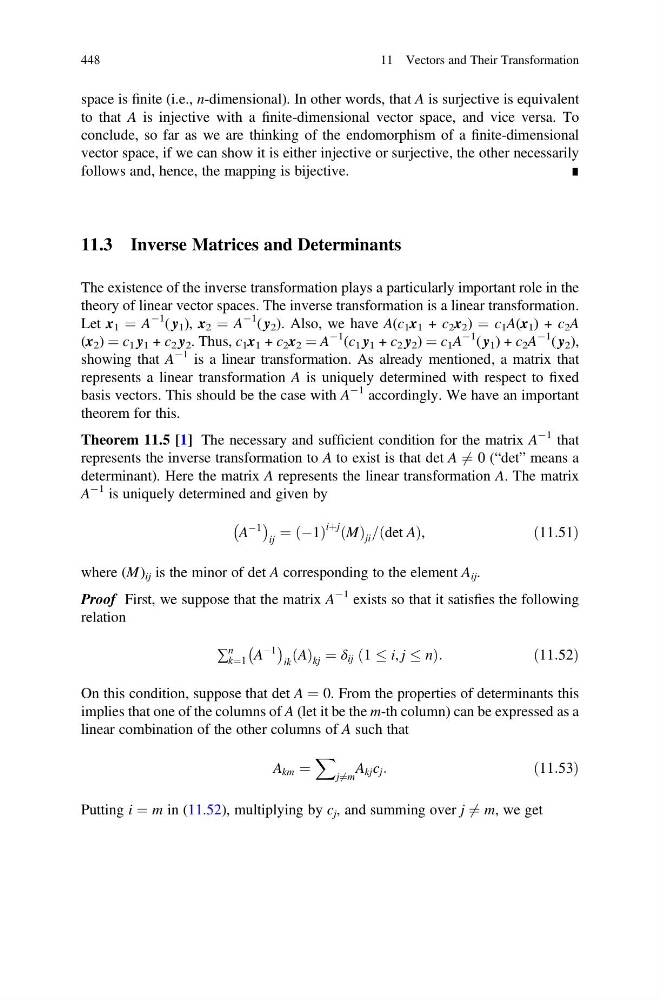
space is finite (i.e., n-dimensional). In other words, that A is surjective is equivalent
to that A is injective with a finite-dimensional vector space, and vice versa. To
conclude, so far as we are thinking of the endomorphism of a finite-dimensional
vector space, if we can show it is either injective or surjective, the other necessarily
follows and, hence, the mapping is bijective.
∎
11.3 Inverse Matrices and Determinants
The existence of the inverse transformation plays a particularly important role in the
theory of linear vector spaces. The inverse transformation is a linear transformation.
Let x 1 ¼ A
À1 ( y 1 ), x 2 ¼ A
À1 ( y 2 ). Also, we have A(c 1 x 1 + c 2 x 2 ) ¼ c 1 A(x 1 ) + c 2 A
(x 2 ) ¼ c 1 y 1 + c 2 y 2 . Thus, c 1 x 1 + c 2 x 2 ¼ A
À1 (c 1 y 1 + c 2 y 2 ) ¼ c 1 A
À1 ( y 1 ) + c 2 A
À1 ( y 2 ),
showing that A
À1 is a linear transformation. As already mentioned, a matrix that
represents a linear transformation A is uniquely determined with respect to fixed
basis vectors. This should be the case with A
À1 accordingly. We have an important
theorem for this.
Theorem 11.5 [1] The necessary and sufficient condition for the matrix A
À1 that
represents the inverse transformation to A to exist is that det A 6 ¼ 0 (“det” means a
determinant). Here the matrix A represents the linear transformation A. The matrix
A
À1 is uniquely determined and given by
A
À1
À
Á
ij
¼ À1
ð Þ
iþj M
ð Þ ji = det A
ð
Þ,
ð11:51Þ
where (M) ij is the minor of det A corresponding to the element A ij .
Proof First, we suppose that the matrix A
À1 exists so that it satisfies the following
relation
∑
n
k¼1 A
À1
À
Á
ik
A
ð Þ kj ¼ δ ij 1 i, j n
ð
Þ :
ð11:52Þ
On this condition, suppose that det A ¼ 0. From the properties of determinants this
implies that one of the columns of A (let it be the m-th column) can be expressed as a
linear combination of the other columns of A such that
A km ¼
X
j6 ¼m
A kj c j :
ð11:53Þ
Putting i ¼ m in (11.52), multiplying by c j , and summing over j 6 ¼ m, we get
448
11 Vectors and Their Transformation