

1.3. Techniques for the Optimization
of a Water Resources System
19
they can be changed into two inequality constraints, or, alternatively,
used to reduce the vector of variables by one variable for each equation.)
Figure 1.7 illustrates the linear programming problem for two variables.
Various methods have been proposed to solve the problem posed by Eqs.
(1.1), references for which can be found in the list of supplementary readings at the end of the book. Probably the best-known method is the revised
simplex method.
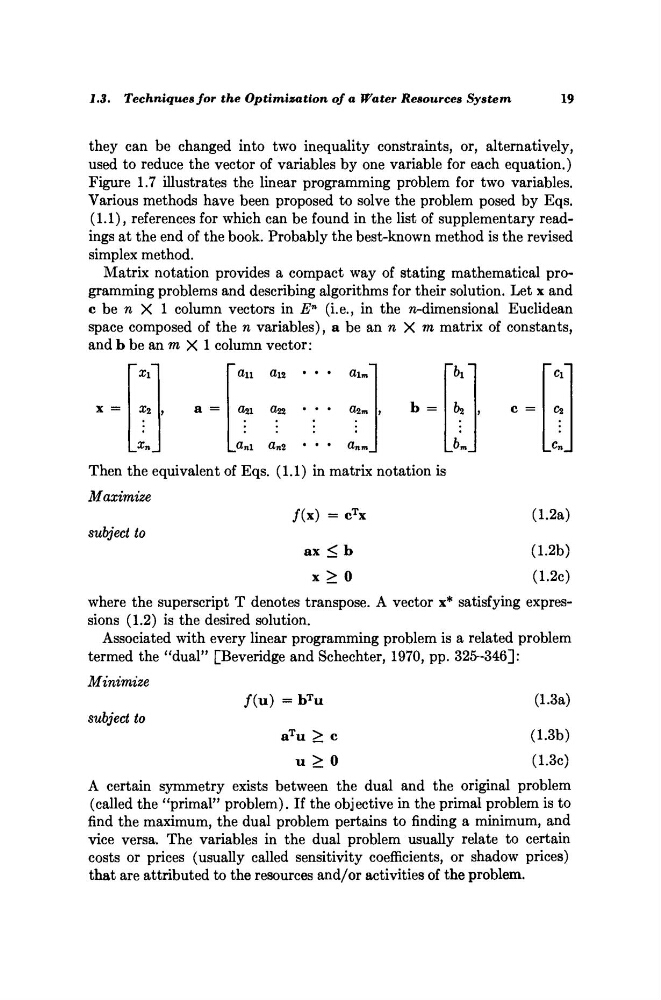
Matrix notation provides a compact way of stating mathematical programming problems and describing algorithms for their solution. Let χ and
c be η X 1 column vectors in E
n
(i.e., in the η-dimensional Euclidean
space composed of the η variables), a be an η X m matrix of constants,
and b be an m X 1 column vector:
an dl2 * ' *
dim
δι
Ci
>
a = 021 #22
' ·
(hm ,
b =
,
c =
JLnl
α Λ 2
· • ·
&ητη_
J)m_
_
C «.
Then the equivalent of Eqs. (1.1) in matrix notation is
Maximize
/(x) = c
T x
(1.2a)
subject to
ax < b
(1.2b)
χ > 0
(1.2c)
where the superscript Τ denotes transpose. A vector x* satisfying expressions (1.2) is the desired solution.
Associated with every linear programming problem is a related problem
termed the "dual" [Beveridge and Schechter, 1970, pp. 325-346]:
Minimize
/(u) = b
T u
(1.3a)
subject to
a
T u > c
(1.3b)
u > 0
(1.3c)
A certain symmetry exists between the dual and the original problem
(called the "primal" problem). If the objective in the primal problem is to
find the maximum, the dual problem pertains to finding a minimum, and
vice versa. The variables in the dual problem usually relate to certain
costs or prices (usually called sensitivity coefficients, or shadow prices)
that are attributed to the resources and/or activities of the problem.