

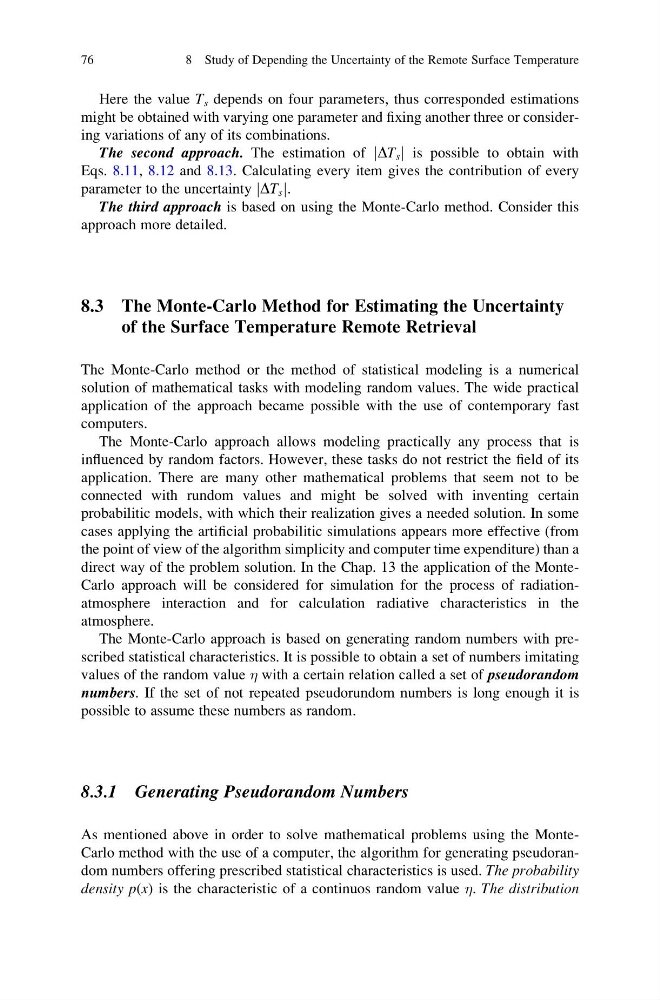
Here the value T s depends on four parameters, thus corresponded estimations
might be obtained with varying one parameter and fixing another three or considering variations of any of its combinations.
The second approach. The estimation of DT s
j
j is possible to obtain with
Eqs. 8.11, 8.12 and 8.13. Calculating every item gives the contribution of every
parameter to the uncertainty DT s
j
j.
The third approach is based on using the Monte-Carlo method. Consider this
approach more detailed.
8.3 The Monte-Carlo Method for Estimating the Uncertainty
of the Surface Temperature Remote Retrieval
The Monte-Carlo method or the method of statistical modeling is a numerical
solution of mathematical tasks with modeling random values. The wide practical
application of the approach became possible with the use of contemporary fast
computers.
The Monte-Carlo approach allows modeling practically any process that is
influenced by random factors. However, these tasks do not restrict the field of its
application. There are many other mathematical problems that seem not to be
connected with rundom values and might be solved with inventing certain
probabilitic models, with which their realization gives a needed solution. In some
cases applying the artificial probabilitic simulations appears more effective (from
the point of view of the algorithm simplicity and computer time expenditure) than a
direct way of the problem solution. In the Chap. 13 the application of the MonteCarlo approach will be considered for simulation for the process of radiationatmosphere interaction and for calculation radiative characteristics in the
atmosphere.
The Monte-Carlo approach is based on generating random numbers with prescribed statistical characteristics. It is possible to obtain a set of numbers imitating
values of the random value with a certain relation called a set of pseudorandom
numbers. If the set of not repeated pseudorundom numbers is long enough it is
possible to assume these numbers as random.
8.3.1 Generating Pseudorandom Numbers
As mentioned above in order to solve mathematical problems using the MonteCarlo method with the use of a computer, the algorithm for generating pseudorandom numbers offering prescribed statistical characteristics is used. The probability
density p(x) is the characteristic of a continuos random value . The distribution
76
8 Study of Depending the Uncertainty of the Remote Surface Temperature