

DATA ASSIMILATION
323
S) fixed-interval smoother. The RTS smoother can be shown to
d
bac
The recursive relation Eq (11) can be recognized as the Rauch-TungStriebel (RT
provide estimates of the state and control using all observations within a
fixed time interval and is a general solution to the assimilation problem (Eq
1). (The smoother alters all filtered estimates except that at the end of the
fixed time-interval; i.e., The Kalman filter estimate at the end of the timeinterval is a least-squares solution of Eq (1) but not at intervening times.)
In Eq (11), past data information is contained in the Kalman filtered
analysis
1
ˆ
a
t
x while information of formally future observations is carrie
kward in time by the smoothed estimate ˆ
s
t
x . Owing to the additional
information from formally future observations, the smoothed estimates are
generally more accurate (has smaller error) than corresponding filtered
estimates. The error covariance matrix of the smoothed estimates 1
ˆ
s
t
x and
1
ˆ
s
t
u (Eq 11), 1
s
t
P and
1
s
t
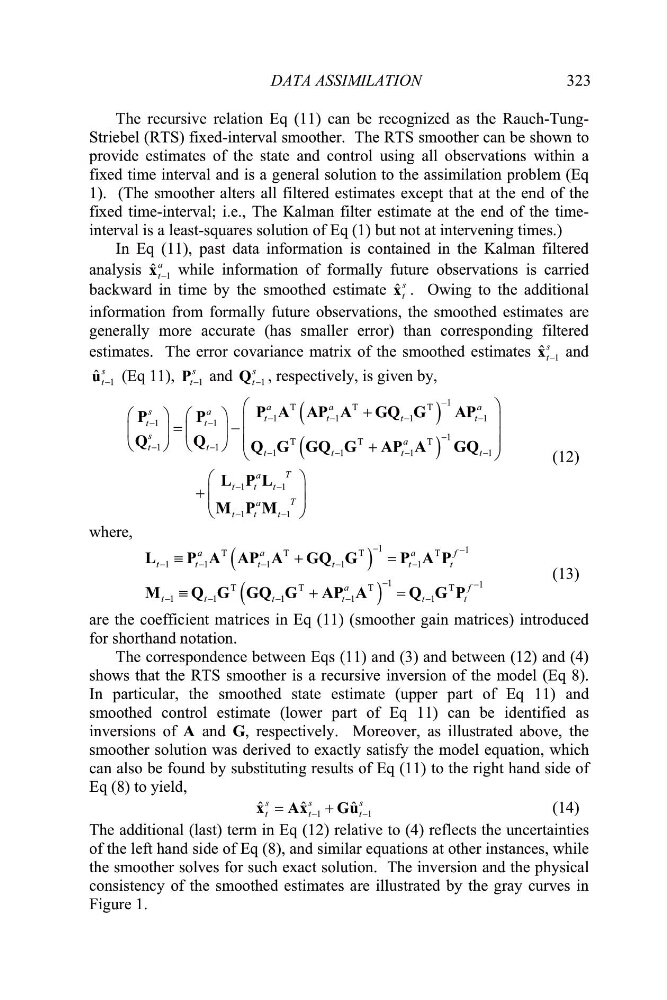
Q , respectively, is given by,
1
T
T
T
1
1
1
1
1
a
a
a
s
a
t
t
t
t
t
s
§
·
§
·
¨
¸
P A AP A GQ G
AP
P
1
1
T
T
T
1
1
1
1
1
1
1
1
1
1
t
a
t
t
t
t
t
t
T
a
t
t
t
T
a
t
t
t
§
· ¨
¸
¨
¸ ¨
¸
¨
¸
©
¹ ©
¹
©
¹
§
·
¨
¸
¨
¸
©
¹
P
Q
Q
Q G GQ G
AP A
GQ
L P L
M P M
(12)
where,
1
1
T
T
T
T
1
1
1
1
1
1
1
T
T
T
T
1
1
1
1
1
a
a
a
f
t
t
t
t
t
t
a
f
t
t
t
t
t
t
{
{
L
P A AP A GQ G
P A P
M
Q G GQ G
AP A
Q G P
(13)
re the coefficient matrices in Eq (11) (smoother gain matr
for shorthand notation.
a
ices) introduced
The correspondence between Eqs (11) and (3) and between (12) and (4)
shows that the RTS smoother is a recursive inversion of the model (Eq 8).
In particular, the smoothed state estimate (upper part of Eq 11) and
smoothed control estimate (lower part of Eq 11) can be identified as
inversions of A and G, respectively. Moreover, as illustrated above, the
smoother solution was derived to exactly satisfy the model equation, which
can also be found by substituting results of Eq (11) to the right hand side of
Eq (8) to yield,
1
1
ˆ
ˆ
ˆ
s
s
s
t
t
t
last) term in Eq (12) relative to (4) reflects the uncertainties
f the left hand side of Eq (8), and similar e
x Ax
Gu
(14)
The additional (
o
quations at other instances, while
the smoother solves for such exact solution. The inversion and the physical
consistency of the smoothed estimates are illustrated by the gray curves in
Figure 1.