

18
Chapter 2: Misuses
insufficient and the Mann-Kenndall test rejects still more null hypotheses
than specified by the significance level.
Another possible cure is to "prune" the data, i.e., to form a sub set of
observations which are temporally weIl separated so that any two consecutive
sampies in the reduced data set are no longer autocorrelated (see Section
9.4.3).
When you use a technique which assumes independent data and you be/ieve
that serial corre/ation might be prevalent in your data, I suggest the following
{{M onte Ca rio " diagnostic: Generate synthetieal time series with a preseribed
serial correlation, for instance by means of an AR(l)-process (2.3). Create
time series without correlation (a = 0) and with eorrelation (0 < a < 1)
and try out if the analysis, which is made with the real data, returns different
results for the cases with and without serial correlation. In the ease that they
are different, you cannot use the chosen technique.
2.4 Misleading N ames: The Case of the
Decorrelation Time
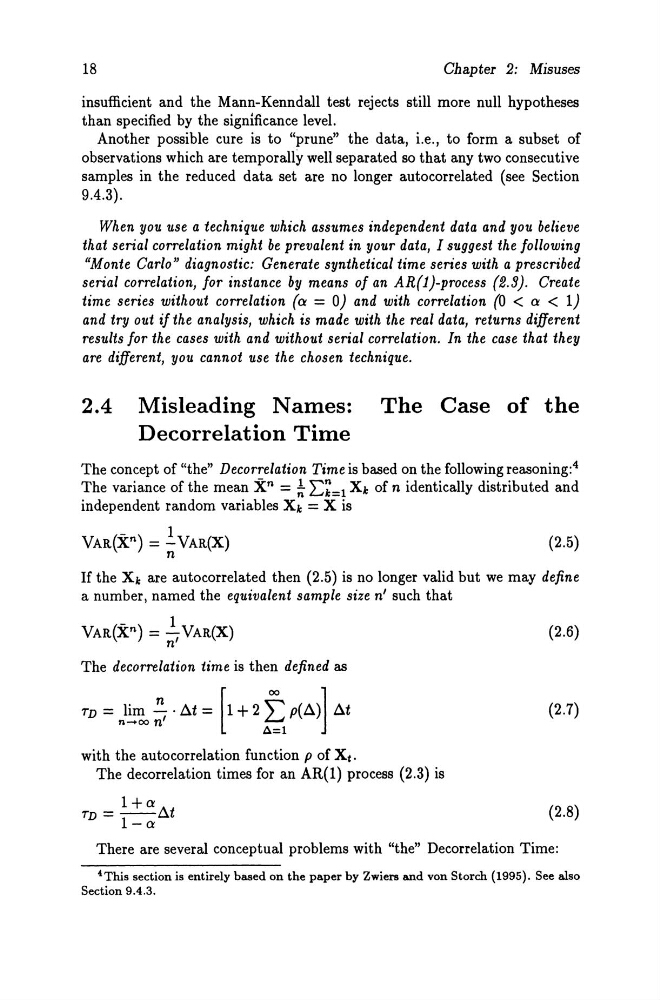
The concept of "the" Decorrelation Time is based on the following reasoning: 4
The variance of the mean X n = ~ E~=1 Xl: of n identically distributed and
independent random variables Xl: = X is
(2.5)
If the Xl: are autocorrelated then (2.5) is no longer valid but we may define
a number, named the equivalent sampie size n' such that
VAR(X n ) = ..!, VAR(X)
n
The decorrelation time is then defined as
TD = !im ~ . At = [1 + 2 ~ p( A)] At
n-oo n'
L..J
.0.=1
with the autocorrelation function p of X t .
The decorrelation times for an AR(1) process (2.3) is
1+a
TD = --At I-a
(2.6)
(2.7)
(2.8)
There are several conceptual problems with "the" Decorrelation Time:
4This section is entirely based on the paper by Zwiers and von Storch (1995). See also
Section 9.4.3.