

Section 15.1: Introduction
283
(non-linear) model is called, according to Hasselmann (1988), a POP (PIP)
model , and the patterns which spanned the "signal" subspace are called
Principal Oscillation Patterns (POPs) for a linear model and Principal Interaction Patterns (PIPs) for a nonlinear model. The contribution from the
"noise" subspace is introduced in a PIP or POP model by a stochatic forcing
term.
The consideration of aphase space consisting of "signal" and "noise" subspaces or a time series having both deterministic and stochastic characters
is also suitable for an AR or MA process. In the case of the AR(I) process,
the deterministic part is represented by the fact that the time series at time
t has a fixed relation to time series at time t - 1. The stochastic part is
represented by a white noise forcing. In this respect, both AR/MA model
and PIP /POP model represent the same category of models. The difference
lies in the way the models are constructed. An AR/MA model is designed for
inferring statistics of a process whereas a POP /PIP model for inferring statistics of the process. Thus, an AR/MA model provides information about the
low-order moments, whereas a POP /PIP model provides information ab out
the dominant dynamics.
In the case that there is no a-priori knowledge of the process of our interest,
it is reasonable to consider the first order approximations of the process. A
linearization of a process can be considered as a first order approximation.
A POP model which is the discrete form of such a linearization is designed
to study the eigenstructure of the process. If Xt represents a time series in
the multivariate "signal" subspace, the model states
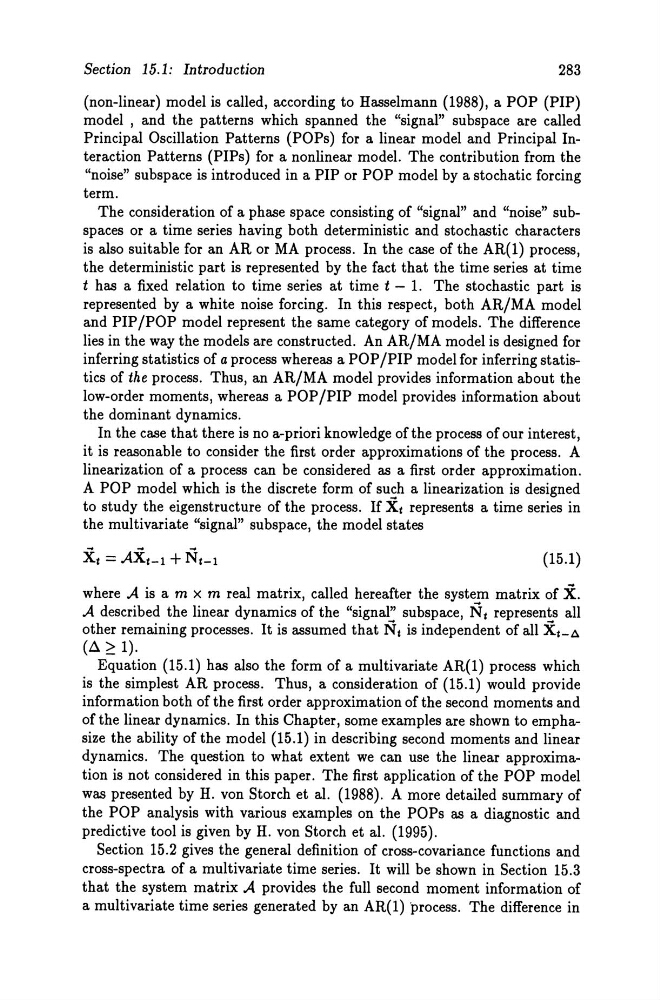
(15.1)
where A is a m x m real matrix, called hereafter the system matrix of X.
A described the linear dynamics of the "signal" subspace, Nt represents all
other remaining processes. It is assumed that Nt is independent of all Xt-A
(~ ~ 1).
Equation (15.1) has also the form of a multivariate AR(I) process which
is the simplest AR process. Thus, a consideration of (15.1) would provide
information both of the first order approximation of the second moments and
ofthe linear dynamics. In this Chapter, some examples are shown to emphasize the ability of the model (15.1) in describing second moments and linear
dynamics. The question to what extent we can use the linear approximation is not considered in this paper. The first application of the POP model
was presented by H. von Storch et al. (1988). A more detailed summary of
the POP analysis with various examples on the POPs as a diagnostic and
predictive tool is given by H. von Storch et al. (1995).
Section 15.2 gives the general definition of cross-covariance functions and
cross-spectra of a multivariate time series. It will be shown in Section 15.3
that the system matrix A provides the fuH second moment information of
a multivariate time series generated by an AR(I) ·process. The difference in