

90
P. Courtier
The random noise depicts the fact that the model is not perfect. Here we assume no bias and no
time correlation and that we know the covariance matrix Q of the model errors. Relaxation of
these assumptions is discussed by Jawinski (1970). At a given time, observations are available
Yi = HiX( t;) + random noise (observation errors).
We assume the covariance matrix of observation errors Oi is known. Then we are in a position
to apply an extended Kalman filter.
The forecast step
The analysis step
with
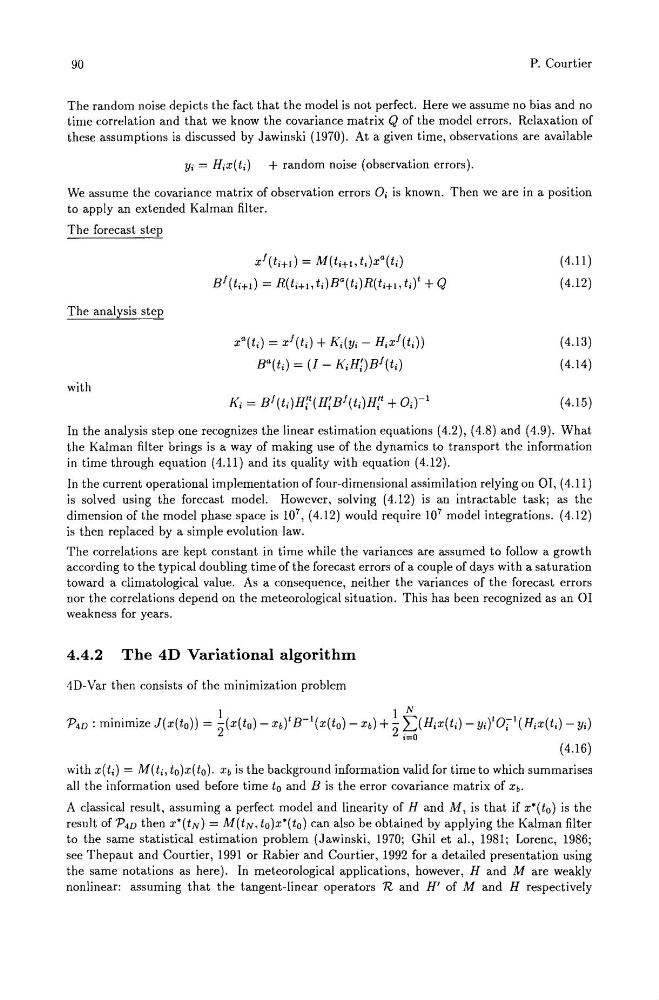
Xf(ti+l) = M(ti+l,ti)Xa(ti)
Bf (ti+d = R(ti+1 ,ti)Ba(t;JR(ti+l, tilt + Q
Xa(ti) = xf(t;) + Ki(Yi - HiXf(ti))
Ba(t;) = (I - KiH!)Bf(ti)
(4.11 )
( 4.12)
(4.13)
(4.14 )
(4.15 )
In the analysis step one recognizes the linear estimation equations (4.2), (4.8) and (4.9). What
the Kalman filter brings is a way of making use of the dynamics to transport the information
in time through equation (4.11) and its quality with equation (4.12).
In the current operational implementation of four-dimensional assimilation relying on 01, (4.11)
is solved using the forecast model. However, solving (4.12) is an intractable task; as the
dimension of the model phase space is 101, (4.12) would require 10 7 model integrations. (4.12)
is then replaced by a simple evolution law.
The correlations are kept constant in time while the variances are assumed to follow a growth
according to the typical doubling time of the forecast errors of a couple of days with a saturation
toward a climatological value. As a consequence, neither the variances of the forecast errors
nor the correlations depend on the meteorological situation. This has been recognized as an 01
weakness for years.
4.4.2 The 4D Variational algorithm
4D- Var then consists of the minimization problem
l i N
P4D : minimize J(x(t o)) = -(x(to) - Xb)t B-I(X(tO) - Xb) + - "L.(Hix(ti) - YirO;l(HiX(ii) - Yi)
2
2 i=O
(4.16)
with X(ti) = M(ti, to)x(to). Xb is the background information valid for time to which summarises
all the information used before time to and B is the error covariance matrix of Xb.
A classical result, assuming a perfect model and linearity of Hand M, is that if x"(to) is the
result of P4D then X"(tN) = M(tN. to)x"(to) can also be obtained by applying the Kalman filter
to the same statistical estimation problem (Jawinski. 1970; Ghil et aI., 1981; Lorenc, 1986;
see Thepaut and Courtier, 1991 or Rabier and Courtier, 1992 for a detailed presentation using
the same notations as here). In meteorological applications, however, Hand M are weakly
nonlinear: assuming that the tangent-linear operators n and H' of M and H respectively