

461
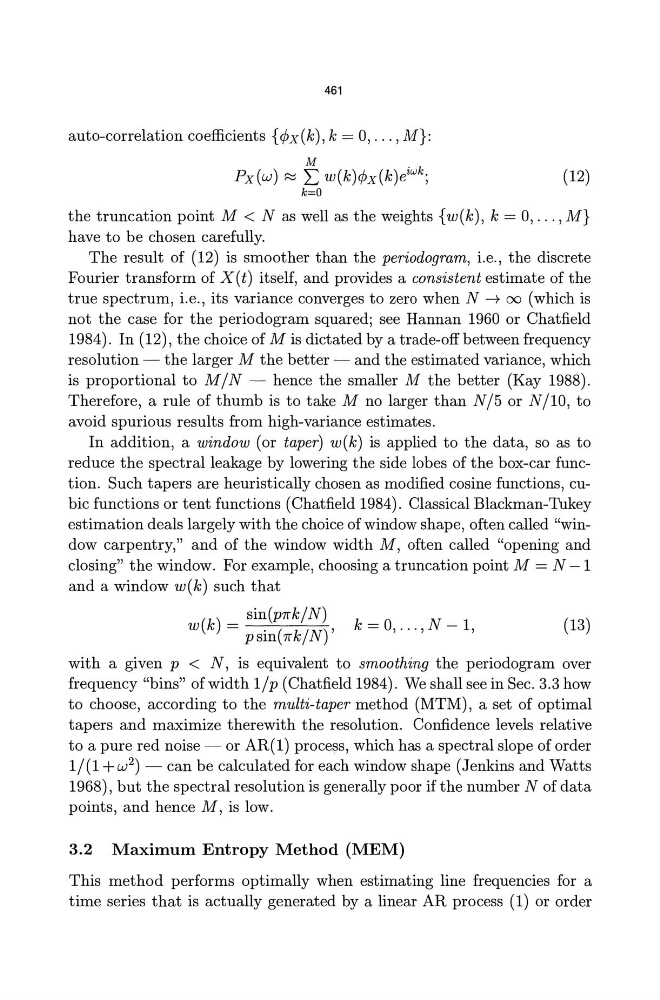
auto-correlation coefficients {¢ x (k ), k = 0, ... , M}:
M
PX(W) ~ L w(k)¢x(k)e iwk ;
(12)
k=O
the truncation point M < N as well as the weights {w (k), k = 0, ... , M}
have to be chosen carefully.
The result of (12) is smoother than the periodogram, i.e., the discrete
Fourier transform of X(t) itself, and provides a consistent estimate of the
true spectrum, i.e., its variance converges to zero when N -t 00 (which is
not the case for the periodogram squared; see Hannan 1960 or Chatfield
1984). In (12), the choice of M is dictated by a trade-off between frequency
resolution - the larger M the better - and the estimated variance, which
is proportional to M/N - hence the smaller M the better (Kay 1988).
Therefore, a rule of thumb is to take M no larger than N /5 or N /10, to
avoid spurious results from high-variance estimates.
In addition, a window (or taper) w(k) is applied to the data, so as to
reduce the spectral leakage by lowering the side lobes of the box-car function. Such tapers are heuristically chosen as modified cosine functions, cubic functions or tent functions (Chatfield 1984). Classical Blackman-Tukey
estimation deals largely with the choice of window shape, often called "window carpentry," and of the window width M, often called "opening and
closing" the window. For example, choosing a truncation point M = N-1
and a window w(k) such that
(k) = sin(p1rk/N)
k
w
psin(1rk/N) '
= 0, ... , N - 1,
(13)
with a given p < N, is equivalent to smoothing the periodogram over
frequency "bins" of width l/p (Chatfield 1984). We shall see in Sec. 3.3 how
to choose, according to the multi-taper method (MTM), a set of optimal
tapers and maximize therewith the resolution. Confidence levels relative
to a pure red noise - or AR(l) process, which has a spectral slope of order
1/(1 +w 2 ) - can be calculated for each window shape (Jenkins and Watts
1968), but the spectral resolution is generally poor ifthe number N of data
points, and hence M, is low.
3.2 Maximum Entropy Method (MEM)
This method performs optimally when estimating line frequencies for a
time series that is actually generated by a linear AR process (1) or order