

446
1 Wherefrom: Introduction and Motivation
The guiding idea of time-series analysis is that certain basic properties of a
physical, biological or socio-economic system that generated the recorded
time series can be detected by its analysis. These properties ~ subject
to validation by using additional information, such as other (segments of)
time series generated by the same system ~ can then be put to good use
by helping predict the system's future behavior.
1.1 Analysis in the time vs. the spectral domain
Two basic approaches to time series analysis are associated with the time
domain or spectral domain. Both are most easily understood in the linear
context in which the physical sciences have operated for most of the last
two centuries. In this context, the physical system can be described by a
(system of) linear, ordinary or partial, differential or difference equation ( s),
subject to additive random forcing. The (constant) coefficients ak of a
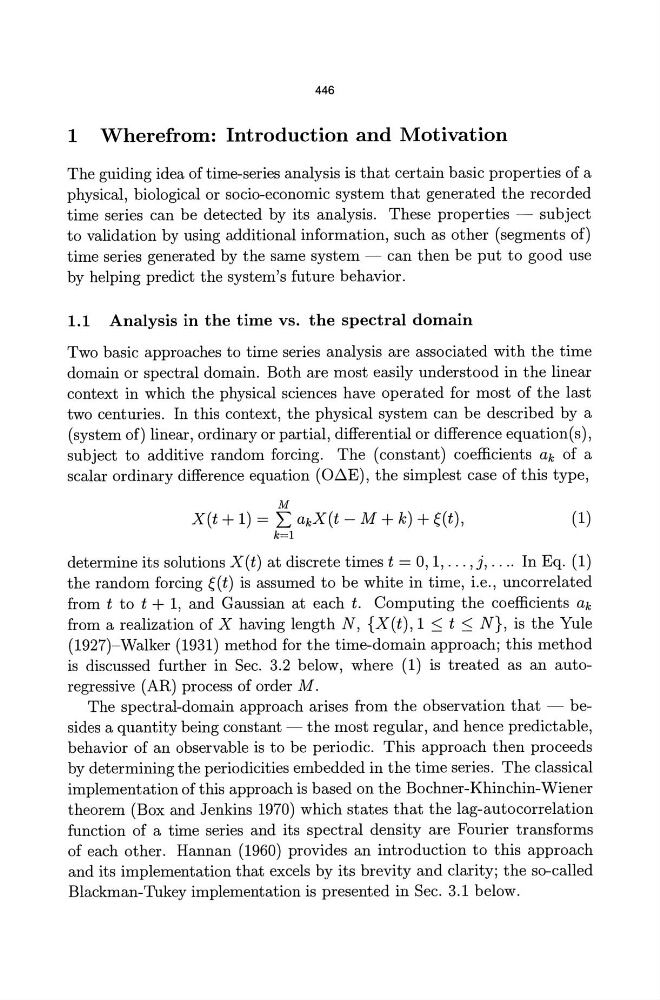
scalar ordinary difference equation (06.E), the simplest case of this type,
M
X (t + 1) = L akX (t - M + k) + e (t),
(1)
k=l
determine its solutions X(t) at discrete times t = 0,1, ... ,j, .... In Eq. (1)
the random forcing e(t) is assumed to be white in time, i.e., uncorrelated
from t to t + 1, and Gaussian at each t. Computing the coefficients ak
from a realization of X having length N, {X(t), 1 :s: t :s: N}, is the Yule
(1927)-Walker (1931) method for the time-domain approach; this method
is discussed further in Sec. 3.2 below, where (1) is treated as an autoregressive (AR) process of order M.
The spectral-domain approach arises from the observation that ~ besides a quantity being constant ~ the most regular, and hence predictable,
behavior of an observable is to be periodic. This approach then proceeds
by determining the periodicities embedded in the time series. The classical
implementation of this approach is based on the Bochner-Khinchin-Wiener
theorem (Box and Jenkins 1970) which states that the lag-autocorrelation
function of a time series and its spectral density are Fourier transforms
of each other. Hannan (1960) provides an introduction to this approach
and its implementation that excels by its brevity and clarity; the so-called
Blackman-Tukey implementation is presented in Sec. 3.1 below.