

7.4 A One-Dimensional Random Surface
165
0
0.1
0.2
0.3
0.4
0.5
0.6
0.7
0.8
0.9
1
0
5
10
15
20
25
30
35
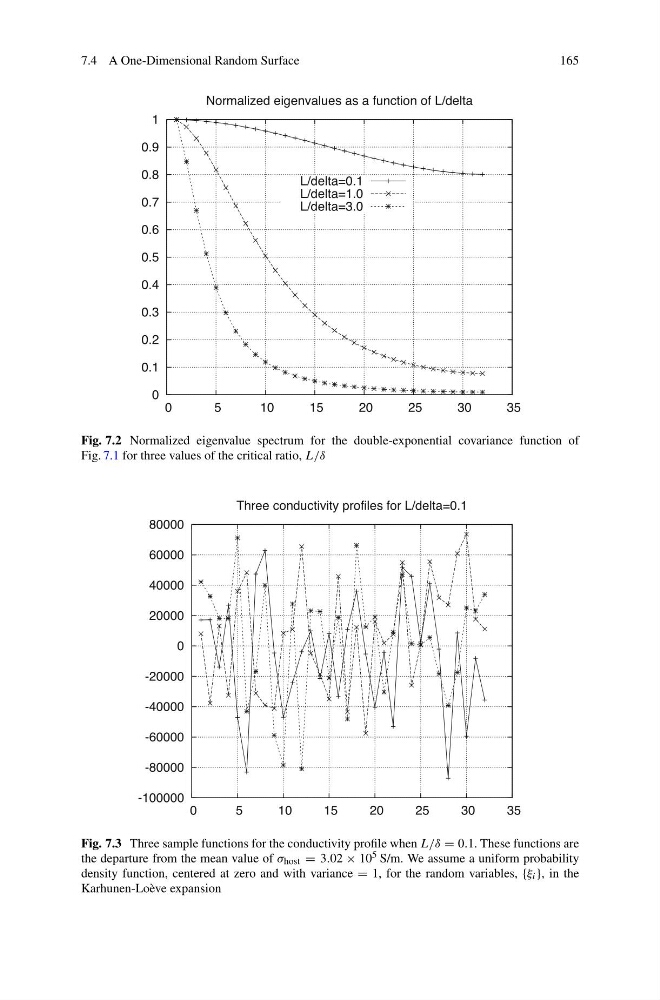
Normalized eigenvalues as a function of L/delta
L/delta=0.1
L/delta=1.0
L/delta=3.0
Fig. 7.2 Normalized eigenvalue spectrum for the double-exponential covariance function of
Fig. 7.1 for three values of the critical ratio, L/δ
-100000
-80000
-60000
-40000
-20000
0
20000
40000
60000
80000
0
5
10
15
20
25
30
35
Three conductivity profiles for L/delta=0.1
Fig. 7.3 Three sample functions for the conductivity profile when L/δ = 0.1. These functions are
the departure from the mean value of σ host = 3.02 × 10 5 S/m. We assume a uniform probability
density function, centered at zero and with variance = 1, for the random variables, {ξ i }, in the
Karhunen-Loève expansion