
194
Appendix J
h k =
−
D eff
τ
2D k
τ k
1 − E
2
k
ln(a k )
1/2
cos(2πb k ),
(J.31)
˜
k (˜ t + ˜ t) = ˜
k E k + ˜
h k
(J.32)
˜
(˜ t + ˜ t) =
3
i=1
˜
k (˜ t + ˜ t)
(J.33)
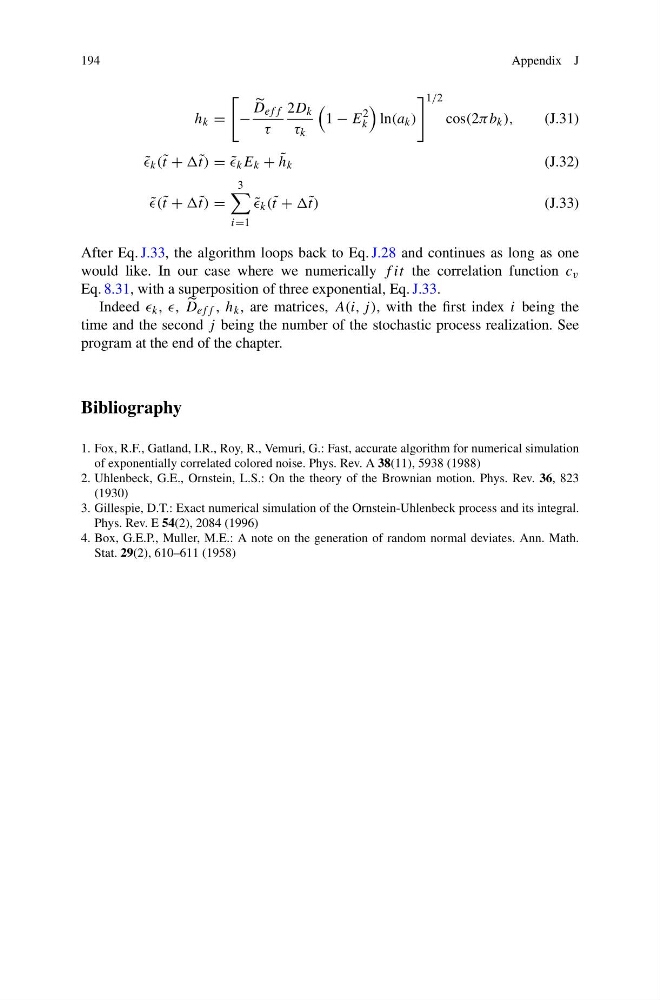
After Eq. J.33, the algorithm loops back to Eq. J.28 and continues as long as one
would like. In our case where we numerically f it the correlation function c v
Eq. 8.31, with a superposition of three exponential, Eq. J.33.
Indeed k , ,
D eff , h k , are matrices, A(i, j ), with the first index i being the
time and the second j being the number of the stochastic process realization. See
program at the end of the chapter.
Bibliography
1. Fox, R.F., Gatland, I.R., Roy, R., Vemuri, G.: Fast, accurate algorithm for numerical simulation
of exponentially correlated colored noise. Phys. Rev. A 38(11), 5938 (1988)
2. Uhlenbeck, G.E., Ornstein, L.S.: On the theory of the Brownian motion. Phys. Rev. 36, 823
(1930)
3. Gillespie, D.T.: Exact numerical simulation of the Ornstein-Uhlenbeck process and its integral.
Phys. Rev. E 54(2), 2084 (1996)
4. Box, G.E.P., Muller, M.E.: A note on the generation of random normal deviates. Ann. Math.
Stat. 29(2), 610–611 (1958)
Précédent