

20
2 Robust Filtering for Multi-model Jumping System
where x F (t) ∈ R
n is the filter state, z F (t) ∈ R
l is the filter output and δ(t) is a
continuous vector-valued initial function. A F (r t ), B F (r t ), C F (r t ) and D F (r t ) are the
filter gain matrices to be designed.
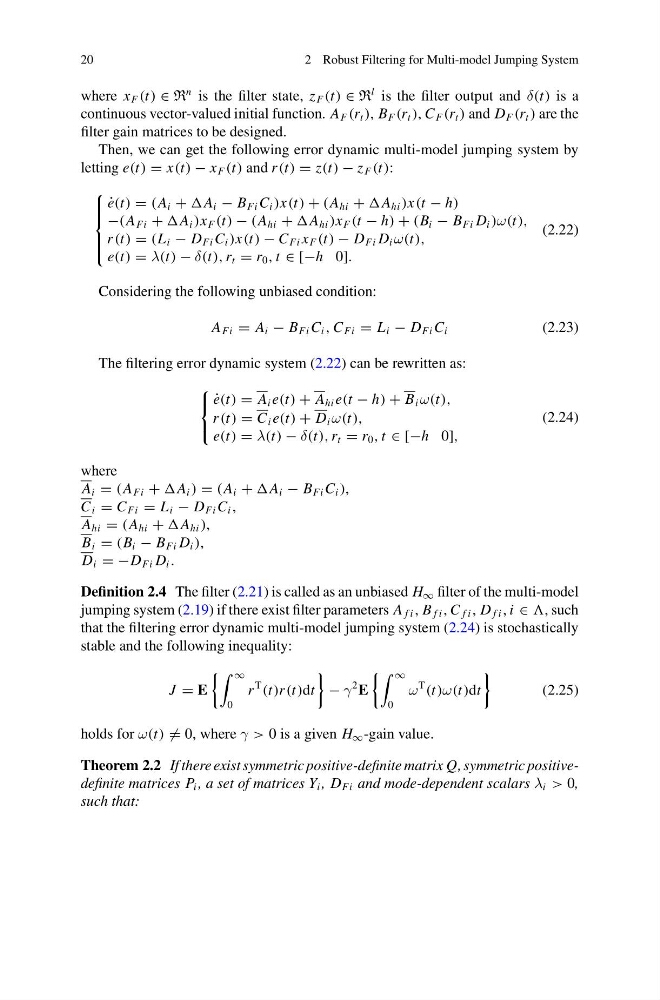
Then, we can get the following error dynamic multi-model jumping system by
letting e(t) = x(t) − x F (t) and r (t) = z(t) − z F (t):
⎧
⎪ ⎪ ⎨
⎪ ⎪ ⎩
˙
e(t) = (A i + A i − B Fi C i )x(t) + (A hi + A hi )x(t − h)
−(A Fi + A i )x F (t) − (A hi + A hi )x F (t − h) + (B i − B Fi D i )ω(t),
r (t) = (L i − D Fi C i )x(t) − C Fi x F (t) − D Fi D i ω(t),
e(t) = λ(t) − δ(t), r t = r 0 , t ∈ [−h 0].
(2.22)
Considering the following unbiased condition:
A Fi = A i − B Fi C i , C Fi = L i − D Fi C i
(2.23)
The filtering error dynamic system (2.22) can be rewritten as:
⎧
⎨
⎩
˙
e(t) = A i e(t) + A hi e(t − h) + B i ω(t),
r (t) = C i e(t) + D i ω(t),
e(t) = λ(t) − δ(t), r t = r 0 , t ∈ [−h 0],
(2.24)
where
A i = (A Fi + A i ) = (A i + A i − B Fi C i ),
C i = C Fi = L i − D Fi C i ,
A hi = (A hi + A hi ),
B i = (B i − B Fi D i ),
D i = −D Fi D i .
Definition 2.4 The filter (2.21) is called as an unbiased H ∞ filter of the multi-model
jumping system (2.19) if there exist filter parameters A f i , B f i , C f i , D f i , i ∈ , such
that the filtering error dynamic multi-model jumping system (2.24) is stochastically
stable and the following inequality:
J = E
∞
0
r
T
(t)r (t)dt
− γ
2 E
∞
0
ω
T
(t)ω(t)dt
(2.25)
holds for ω(t) = 0, where γ > 0 is a given H ∞ -gain value.
Theorem 2.2 If there exist symmetric positive-definite matrix Q, symmetric positivedefinite matrices P i , a set of matrices Y i , D Fi and mode-dependent scalars λ i > 0,
such that: