

16
2 Robust Filtering for Multi-model Jumping System
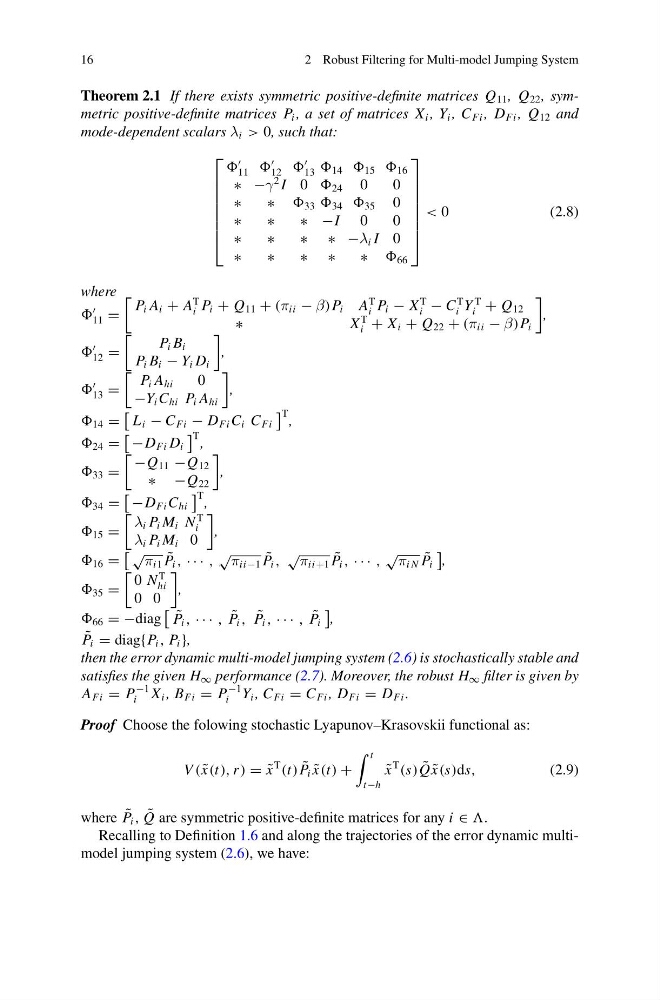
Theorem 2.1 If there exists symmetric positive-definite matrices Q 11 , Q 22 , symmetric positive-definite matrices P i , a set of matrices X i , Y i , C Fi , D Fi , Q 12 and
mode-dependent scalars λ i > 0, such that:
⎡
⎢
⎢
⎢
⎢
⎢
⎢
⎣
11
12
13 14 15 16
∗ −γ
2 I 0 24 0
0
∗
∗ 33 34 35 0
∗
∗
∗ −I 0
0
∗
∗
∗ ∗ −λ i I 0
∗
∗
∗ ∗
∗ 66
⎤
⎥
⎥
⎥
⎥
⎥
⎥
⎦
< 0
(2.8)
where
11 =
P i A i + A
T
i P i + Q 11 + (π ii − β)P i A
T
i P i − X
T
i − C
T
i Y
T
i + Q 12
∗
X
T
i + X i + Q 22 + (π ii − β)P i
,
12 =
P i B i
P i B i − Y i D i
,
13 =
P i A hi
0
−Y i C hi P i A hi
,
14 =
L i − C Fi − D Fi C i C Fi
T ,
24 =
−D Fi D i
T ,
33 =
−Q 11 −Q 12
∗ −Q 22
,
34 =
−D Fi C hi
T ,
15 =
λ i P i M i N
T
i
λ i P i M i 0
,
16 =
√ π i1 ˜
P i , · · · ,
√ π ii−1 ˜
P i ,
√ π ii+1 ˜
P i , · · · ,
√ π i N ˜
P i
,
35 =
0 N
T
hi
0 0
,
66 = −diag
˜
P i , · · · , ˜
P i , ˜
P i , · · · , ˜
P i
,
˜
P i = diag{P i , P i },
then the error dynamic multi-model jumping system (2.6) is stochastically stable and
satisfies the given H ∞ performance (2.7). Moreover, the robust H ∞ filter is given by
A Fi = P
−1
i X i , B Fi = P
−1
i Y i , C Fi = C Fi , D Fi = D Fi .
Proof Choose the folowing stochastic Lyapunov–Krasovskii functional as:
V ( ˜
x(t), r ) = ˜
x
T
(t) ˜
P i ˜
x(t) +
t
t−h
˜
x
T
(s) ˜
Q ˜
x(s)ds,
(2.9)
where ˜
P i , ˜
Q are symmetric positive-definite matrices for any i ∈ .
Recalling to Definition 1.6 and along the trajectories of the error dynamic multimodel jumping system (2.6), we have: