

The Largest Pool Size and Its Distribution
205
[ ] [ ]
∞
∞
=
=
=
=
∑
∑
*
( )
1
1
E
P (
) E
E
r
r
n
X
n N=n
X
T
(C.9)
Generation of Reservoir Parameters for a Given Pool Size
For the economic analysis of petroleum resources, it is necessary to
fi nd the conditional distribution Z 1 , Z 2 , ... , Z p–1 of Equation C.3 for a
given pool size x. This conditional distribution is also of interest in
exploration.
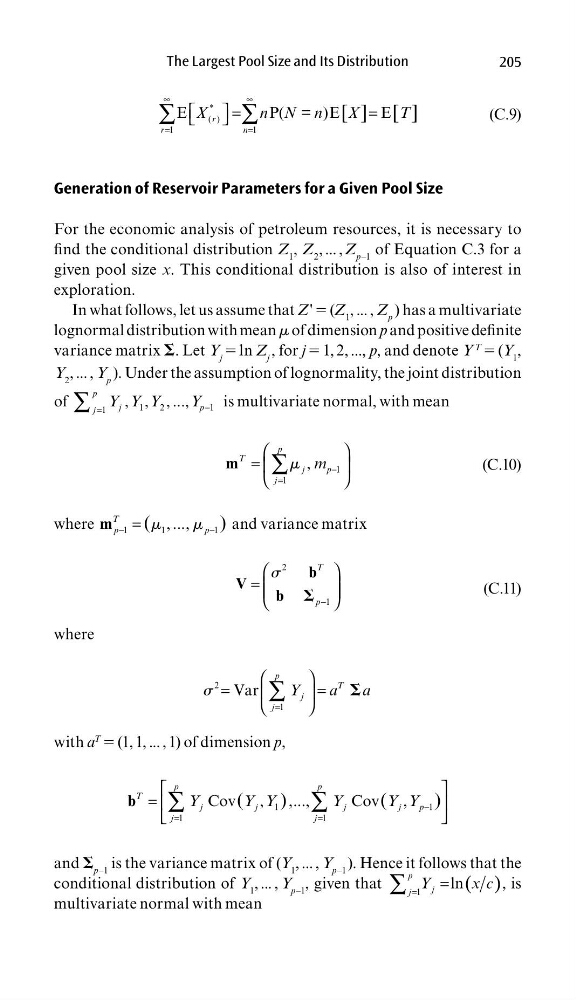
In what follows, let us assume that Z' 5 (Z 1 , ... , Z p ) has a multivariate
lognormal distribution with mean m of dimension p and positive defi nite
variance matrix ⌺. Let Y j 5 ln Z j , for j 5 1, 2, ..., p, and denote Y
T
5 (Y 1 ,
Y 2 , ... , Y p ). Under the assumption of lognormality, the joint distribution
of
1
2
1
1
, , , ...,
p
j
p
j
Y Y Y
Y −
=
∑
is multivariate normal, with mean
−
=
=
∑
1
1
,
p
T
j
p
j
m
m
m
(C.10)
where
−
−
=
1
1
1
, ...,
(
)
T
p
p
m
m
m
and variance matrix
2
1
T
p−
=
b
V
b
s
⌺
(C.11)
where
=
=
=
∑
2
1
Var
p
T
j
j
Y
a
a
s
⌺
with a
T
5 (1, 1, ... , 1) of dimension p,
−
=
=
=
∑
∑
1
1
1
1
Cov
,
,...,
Cov
,
(
)
(
)
p
p
T
j
j
j
j
p
j
j
Y
Y Y
Y
Y Y
b
and ⌺ p–1 is the variance matrix of (Y 1 , ... , Y p–1 ). Hence it follows that the
conditional distribution of Y 1 , ... , Y p–1 , given that
( )
=
=
∑ 1 ln
p
j
j
Y
x c , is
multivariate normal with mean