

6 The Impacts of Electric Vehicles …
203
Table 6.1 (continued)
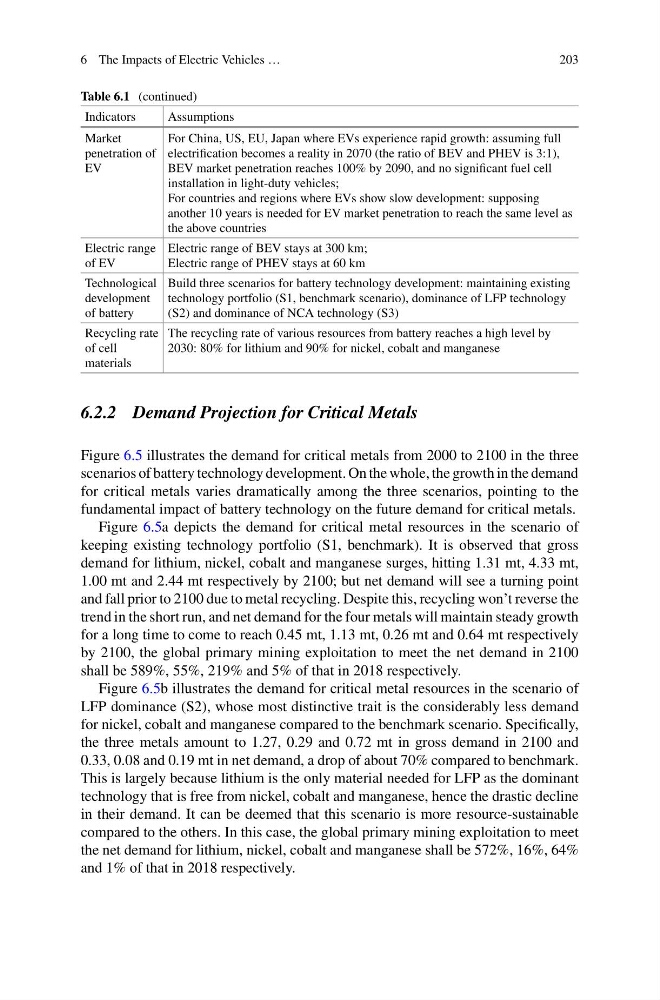
Indicators
Assumptions
Market
penetration of
EV
For China, US, EU, Japan where EVs experience rapid growth: assuming full
electrification becomes a reality in 2070 (the ratio of BEV and PHEV is 3:1),
BEV market penetration reaches 100% by 2090, and no significant fuel cell
installation in light-duty vehicles;
For countries and regions where EVs show slow development: supposing
another 10 years is needed for EV market penetration to reach the same level as
the above countries
Electric range
of EV
Electric range of BEV stays at 300 km;
Electric range of PHEV stays at 60 km
Technological
development
of battery
Build three scenarios for battery technology development: maintaining existing
technology portfolio (S1, benchmark scenario), dominance of LFP technology
(S2) and dominance of NCA technology (S3)
Recycling rate
of cell
materials
The recycling rate of various resources from battery reaches a high level by
2030: 80% for lithium and 90% for nickel, cobalt and manganese
6.2.2 Demand Projection for Critical Metals
Figure 6.5 illustrates the demand for critical metals from 2000 to 2100 in the three
scenarios of battery technology development. On the whole, the growth in the demand
for critical metals varies dramatically among the three scenarios, pointing to the
fundamental impact of battery technology on the future demand for critical metals.
Figure 6.5a depicts the demand for critical metal resources in the scenario of
keeping existing technology portfolio (S1, benchmark). It is observed that gross
demand for lithium, nickel, cobalt and manganese surges, hitting 1.31 mt, 4.33 mt,
1.00 mt and 2.44 mt respectively by 2100; but net demand will see a turning point
and fall prior to 2100 due to metal recycling. Despite this, recycling won’t reverse the
trend in the short run, and net demand for the four metals will maintain steady growth
for a long time to come to reach 0.45 mt, 1.13 mt, 0.26 mt and 0.64 mt respectively
by 2100, the global primary mining exploitation to meet the net demand in 2100
shall be 589%, 55%, 219% and 5% of that in 2018 respectively.
Figure 6.5b illustrates the demand for critical metal resources in the scenario of
LFP dominance (S2), whose most distinctive trait is the considerably less demand
for nickel, cobalt and manganese compared to the benchmark scenario. Specifically,
the three metals amount to 1.27, 0.29 and 0.72 mt in gross demand in 2100 and
0.33, 0.08 and 0.19 mt in net demand, a drop of about 70% compared to benchmark.
This is largely because lithium is the only material needed for LFP as the dominant
technology that is free from nickel, cobalt and manganese, hence the drastic decline
in their demand. It can be deemed that this scenario is more resource-sustainable
compared to the others. In this case, the global primary mining exploitation to meet
the net demand for lithium, nickel, cobalt and manganese shall be 572%, 16%, 64%
and 1% of that in 2018 respectively.