

13 A Critical Intertemporal Analysis of Uganda’s Fiscal Regime …
419
generate similar AETRs from the Buliisa Development between 81 and
84%. Utilizing a discount rate of 10%, the 2012 EA1A PSAs generates
an AETR of 98% and the 2004 EA1 and EA3A PSAs yield AETRs of
95%. This is due to the fact that the 10% discount rate is close to the
Post Tax contractor IRRs of 10.66% under the 2012 EA1A PSA, 11.86%
under the EA1 2004 PSA and 11.66% under the EA3A 2004 PSA. The
theoretical R-factor regime generates an AETR of 91% for the Buliisa
development at a 10% discount rate.
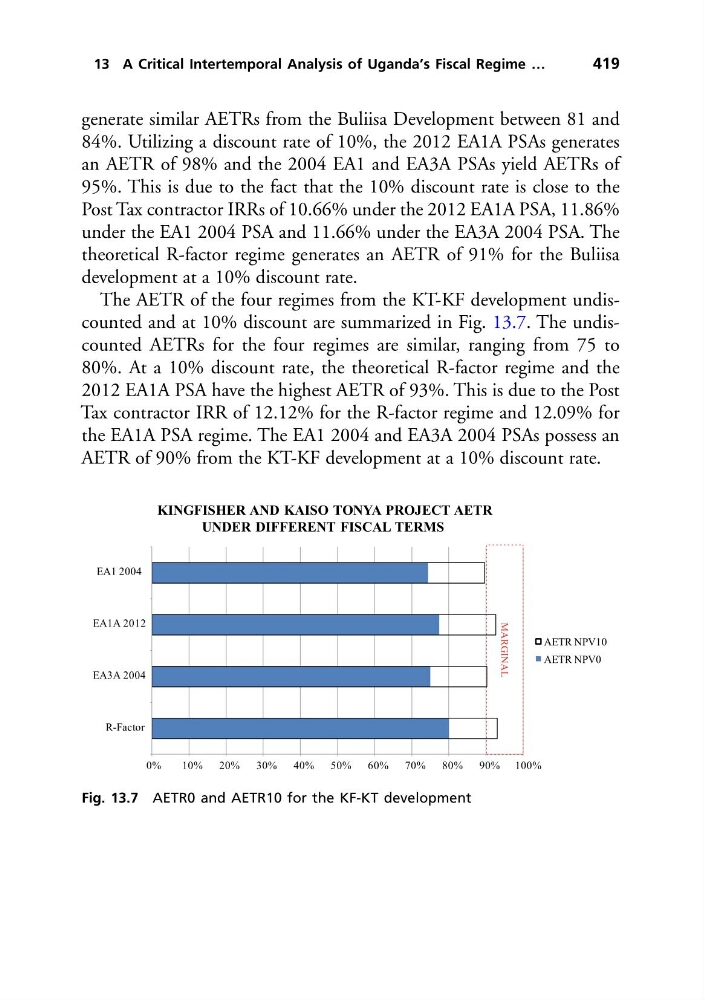
The AETR of the four regimes from the KT-KF development undiscounted and at 10% discount are summarized in Fig. 13.7. The undiscounted AETRs for the four regimes are similar, ranging from 75 to
80%. At a 10% discount rate, the theoretical R-factor regime and the
2012 EA1A PSA have the highest AETR of 93%. This is due to the Post
Tax contractor IRR of 12.12% for the R-factor regime and 12.09% for
the EA1A PSA regime. The EA1 2004 and EA3A 2004 PSAs possess an
AETR of 90% from the KT-KF development at a 10% discount rate.
0%
10%
20%
30%
40%
50%
60%
70%
80%
90% 100%
R-Factor
EA3A 2004
EA1A 2012
EA1 2004
KINGFISHER AND KAISO TONYA PROJECT AETR
UNDER DIFFERENT FISCAL TERMS
AETR NPV10
AETR NPV0
MARGINAL
Fig. 13.7 AETR0 and AETR10 for the KF-KT development