

136
B Linear Differential Equations
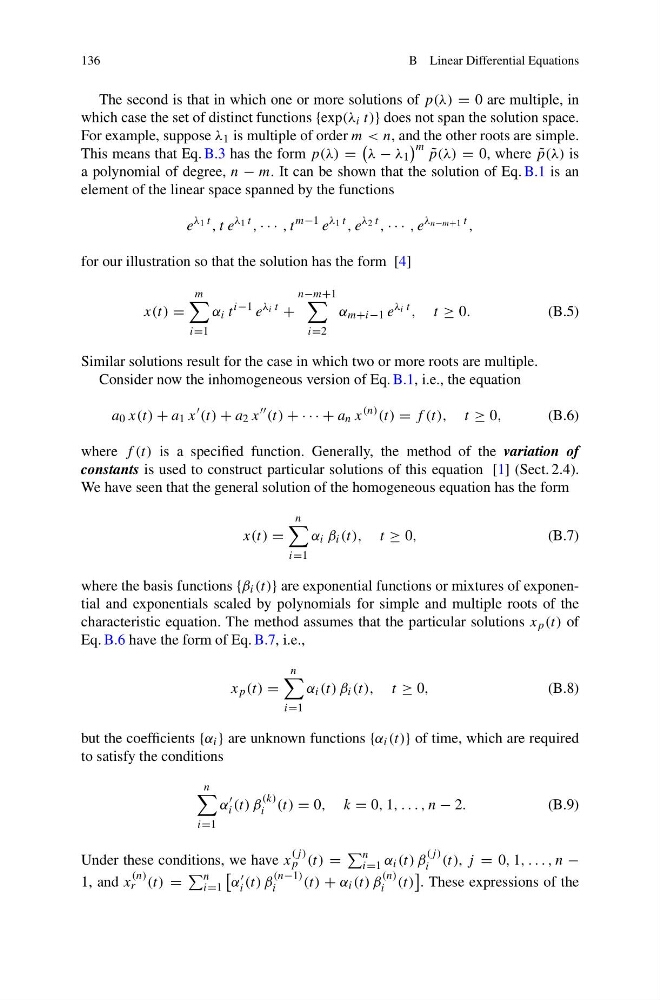
The second is that in which one or more solutions of p(λ) = 0 are multiple, in
which case the set of distinct functions {exp(λ i t)} does not span the solution space.
For example, suppose λ 1 is multiple of order m < n, and the other roots are simple.
This means that Eq. B.3 has the form p(λ) =
λ − λ 1
m ˜
p(λ) = 0, where ˜
p(λ) is
a polynomial of degree, n − m. It can be shown that the solution of Eq. B.1 is an
element of the linear space spanned by the functions
e
λ 1 t , t e
λ 1 t , · · · , t
m−1 e
λ 1 t , e
λ 2 t , · · · , e
λ n−m+1 t ,
for our illustration so that the solution has the form [4]
x(t) =
m
i=1
α i t
i−1 e
λ i t
+
n−m+1
i=2
α m+i−1 e
λ i t , t ≥ 0.
(B.5)
Similar solutions result for the case in which two or more roots are multiple.
Consider now the inhomogeneous version of Eq. B.1, i.e., the equation
a 0 x(t) + a 1 x
(t) + a 2 x
(t) + · · · + a n x
(n) (t) = f (t), t ≥ 0,
(B.6)
where f (t) is a specified function. Generally, the method of the variation of
constants is used to construct particular solutions of this equation [1] (Sect. 2.4).
We have seen that the general solution of the homogeneous equation has the form
x(t) =
n
i=1
α i β i (t), t ≥ 0,
(B.7)
where the basis functions {β i (t)} are exponential functions or mixtures of exponential and exponentials scaled by polynomials for simple and multiple roots of the
characteristic equation. The method assumes that the particular solutions x p (t) of
Eq. B.6 have the form of Eq. B.7, i.e.,
x p (t) =
n
i=1
α i (t) β i (t), t ≥ 0,
(B.8)
but the coefficients {α i } are unknown functions {α i (t)} of time, which are required
to satisfy the conditions
n
i=1
α
i (t) β
(k)
i (t) = 0, k = 0, 1, . . . , n − 2.
(B.9)
Under these conditions, we have x
(j )
p (t) =
n
i=1 α i (t) β
(j )
i (t), j = 0, 1, . . . , n −
1, and x
(n)
r (t) =
n
i=1
α
i (t) β
(n−1)
i
(t) + α i (t) β
(n)
i (t)
. These expressions of the