

542
15 Random Vibrations
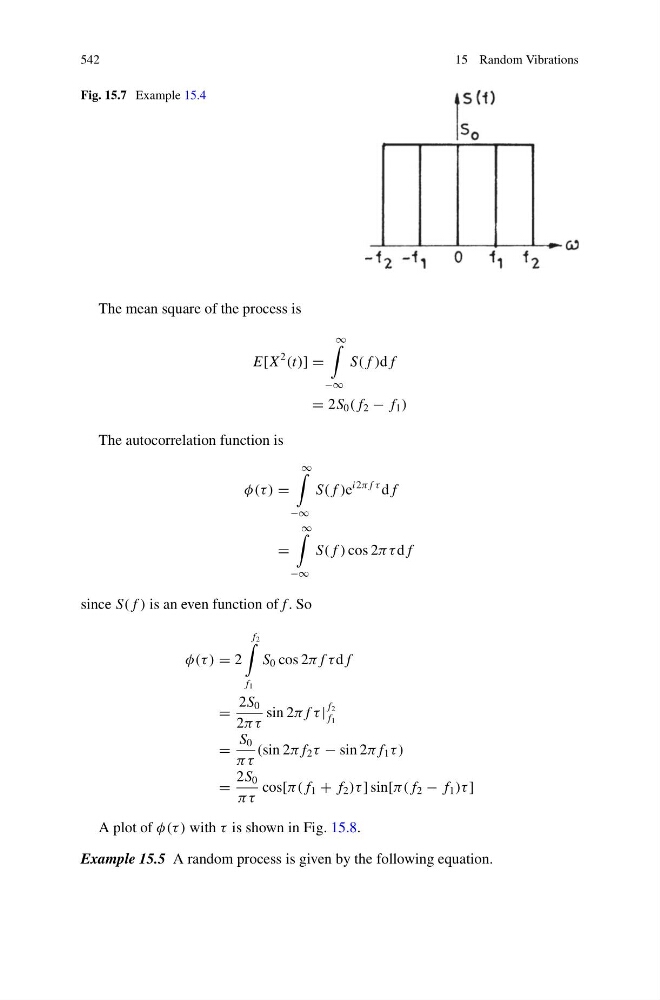
Fig. 15.7 Example 15.4
The mean square of the process is
E[X
2
(t)] =
∞
−∞
S( f )d f
= 2S 0 ( f 2 − f 1 )
The autocorrelation function is
φ(τ ) =
∞
−∞
S( f )e
i2π f τ d f
=
∞
−∞
S( f ) cos 2πτ d f
since S( f ) is an even function of f . So
φ(τ ) = 2
f 2
f 1
S 0 cos 2π f τ d f
=
2S 0
2πτ
sin 2π f τ |
f 2
f 1
=
S 0
πτ
(sin 2π f 2 τ − sin 2π f 1 τ )
=
2S 0
πτ
cos[π( f 1 + f 2 )τ ] sin[π( f 2 − f 1 )τ ]
A plot of φ(τ ) with τ is shown in Fig. 15.8.
Example 15.5 A random process is given by the following equation.