

540
15 Random Vibrations
F
2
(t)
=
∞
−∞
S( f )d f
(15.30)
where
S( f ) =
1
T
|F( f )|
2
(15.31)
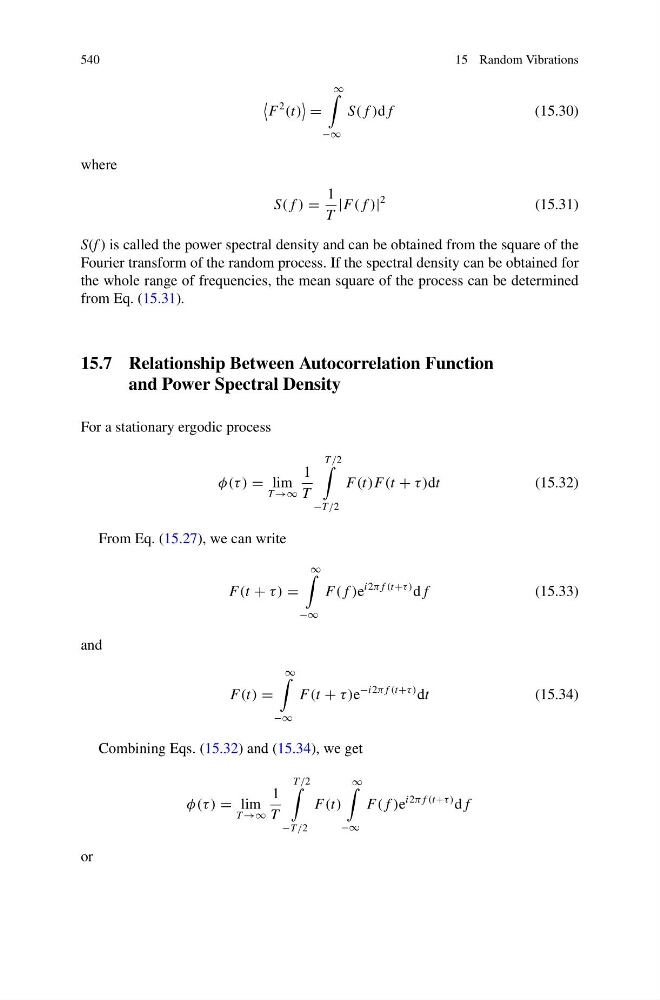
S(f ) is called the power spectral density and can be obtained from the square of the
Fourier transform of the random process. If the spectral density can be obtained for
the whole range of frequencies, the mean square of the process can be determined
from Eq. (15.31).
15.7 Relationship Between Autocorrelation Function
and Power Spectral Density
For a stationary ergodic process
φ(τ ) = lim
T →∞
1
T
T /2
−T /2
F(t)F(t + τ )dt
(15.32)
From Eq. (15.27), we can write
F(t + τ ) =
∞
−∞
F( f )e
i2π f (t+τ ) d f
(15.33)
and
F(t) =
∞
−∞
F(t + τ )e
−i2π f (t+τ ) dt
(15.34)
Combining Eqs. (15.32) and (15.34), we get
φ(τ ) = lim
T →∞
1
T
T /2
−T /2
F(t)
∞
−∞
F( f )e
i2π f (t+τ ) d f
or