

or movements in ‘market sentiment’. The rate at which portfolios have been turned
over has been rising, as investors have held stocks for shorter periods.
12 At the
extreme, high-frequency investors use automated strategies to buy and sell in
fractions of seconds and now account for three-quarters of trading on the New
York Stock Exchange.
13
Increasing short-termism can be seen in banking, where the incentives facing
senior managers of banks encourage the maximization of short-term profits (Dallas,
2012). In the 1970s, the overwhelming majority of banks’ revenues came from
lending. By the 1990s, 35 per cent of US banks revenues came from trading activities
and by 2007 this had risen to 50 per cent (Boot and Ratnovski, 2012).
Financing green transformations 157
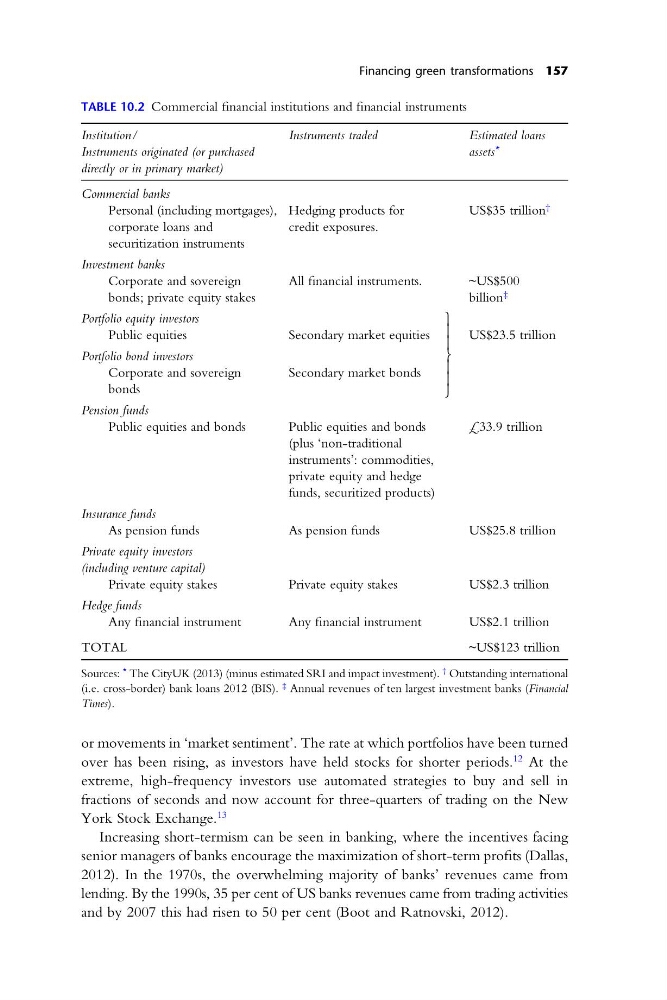
TABLE 10.2 Commercial financial institutions and financial instruments
Institution/
Instruments traded
Estimated loans
Instruments originated (or purchased
assets
*
directly or in primary market)
Commercial banks
Personal (including mortgages), Hedging products for
US$35 trillion
†
corporate loans and
credit exposures.
securitization instruments
Investment banks
Corporate and sovereign
All financial instruments.
~US$500
bonds; private equity stakes
billion
‡
Portfolio equity investors
Public equities
Secondary market equities
US$23.5 trillion
Portfolio bond investors
Corporate and sovereign
Secondary market bonds
bonds
Pension funds
Public equities and bonds
Public equities and bonds
£33.9 trillion
(plus ‘non-traditional
instruments’: commodities,
private equity and hedge
funds, securitized products)
Insurance funds
As pension funds
As pension funds
US$25.8 trillion
Private equity investors
(including venture capital)
Private equity stakes
Private equity stakes
US$2.3 trillion
Hedge funds
Any financial instrument
Any financial instrument
US$2.1 trillion
TOTAL
~US$123 trillion
Sources:
* The CityUK (2013) (minus estimated SRI and impact investment).
† Outstanding international
(i.e. cross-border) bank loans 2012 (BIS).
‡ Annual revenues of ten largest investment banks (Financial
Times).
⎫
⎪
⎪
⎬
⎪
⎪
⎭