

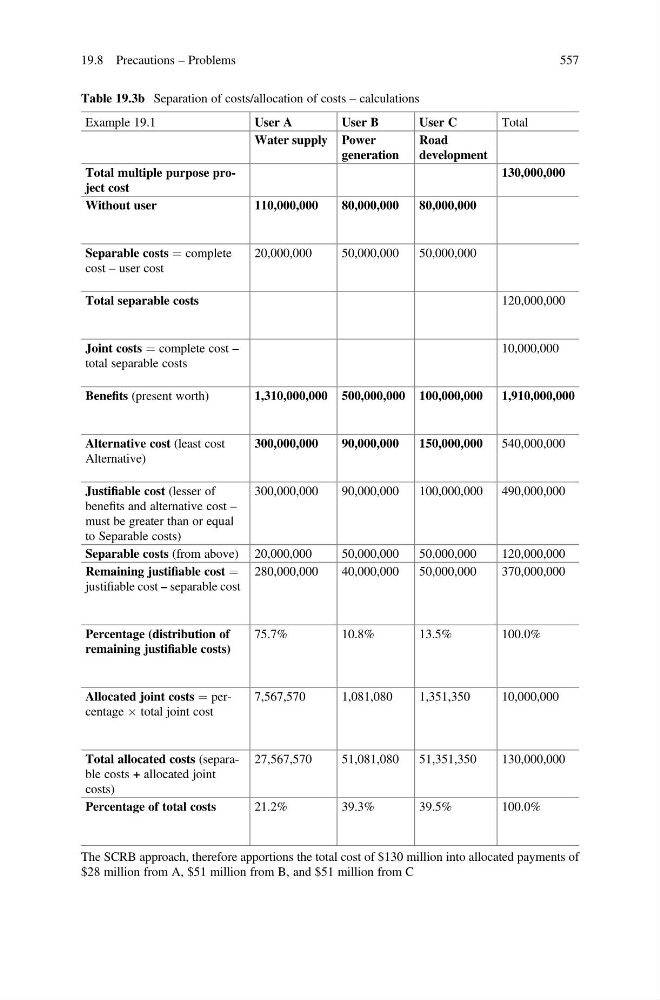
Table 19.3b Separation of costs/allocation of costs – calculations
Example 19.1
User A
User B
User C
Total
Water supply Power
generation
Road
development
Total multiple purpose project cost
130,000,000
Without user
110,000,000
80,000,000
80,000,000
Separable costs ¼ complete
cost – user cost
20,000,000
50,000,000
50,000,000
Total separable costs
120,000,000
Joint costs ¼ complete cost –
total separable costs
10,000,000
Benefits (present worth)
1,310,000,000 500,000,000 100,000,000 1,910,000,000
Alternative cost (least cost
Alternative)
300,000,000
90,000,000
150,000,000 540,000,000
Justifiable cost (lesser of
benefits and alternative cost –
must be greater than or equal
to Separable costs)
300,000,000
90,000,000
100,000,000 490,000,000
Separable costs (from above) 20,000,000
50,000,000
50,000,000
120,000,000
Remaining justifiable cost ¼
justifiable cost – separable cost
280,000,000
40,000,000
50,000,000
370,000,000
Percentage (distribution of
remaining justifiable costs)
75.7%
10.8%
13.5%
100.0%
Allocated joint costs ¼ percentage  total joint cost
7,567,570
1,081,080
1,351,350
10,000,000
Total allocated costs (separable costs + allocated joint
costs)
27,567,570
51,081,080
51,351,350
130,000,000
Percentage of total costs
21.2%
39.3%
39.5%
100.0%
The SCRB approach, therefore apportions the total cost of $130 million into allocated payments of
$28 million from A, $51 million from B, and $51 million from C
19.8 Precautions – Problems
557