

302
K. A. Rybakov
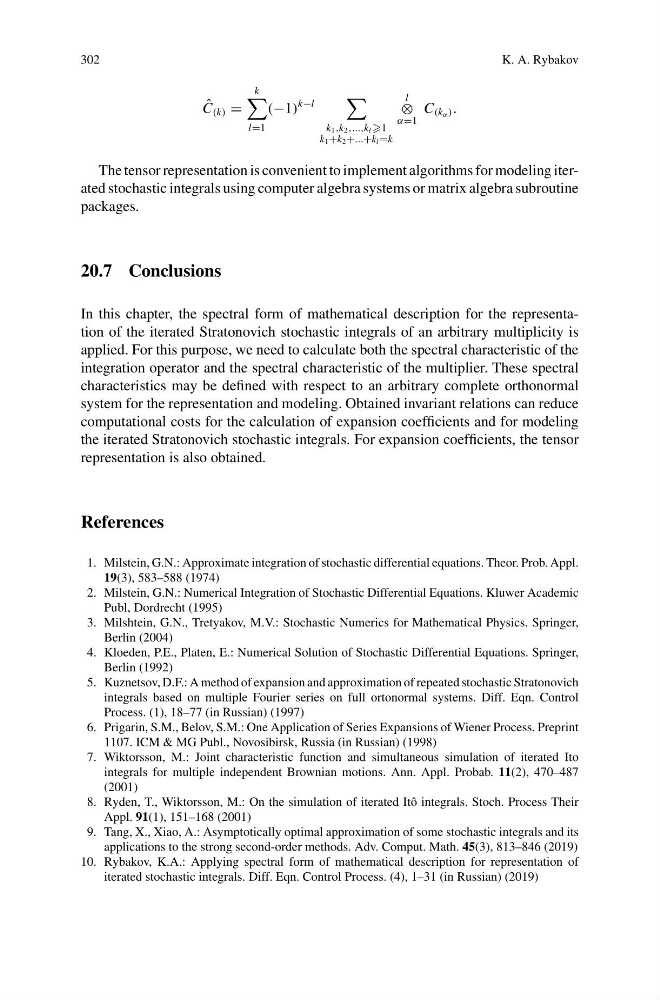
ˆ
C (k) =
k
l=1
(−1)
k−l
k 1 ,k 2 ,...,k l 1
k 1 +k 2 +...+k l =k
l
⊗
α=1
C (k α ) .
The tensor representation is convenient to implement algorithms for modeling iterated stochastic integrals using computer algebra systems or matrix algebra subroutine
packages.
20.7 Conclusions
In this chapter, the spectral form of mathematical description for the representation of the iterated Stratonovich stochastic integrals of an arbitrary multiplicity is
applied. For this purpose, we need to calculate both the spectral characteristic of the
integration operator and the spectral characteristic of the multiplier. These spectral
characteristics may be defined with respect to an arbitrary complete orthonormal
system for the representation and modeling. Obtained invariant relations can reduce
computational costs for the calculation of expansion coefficients and for modeling
the iterated Stratonovich stochastic integrals. For expansion coefficients, the tensor
representation is also obtained.
References
1. Milstein, G.N.: Approximate integration of stochastic differential equations. Theor. Prob. Appl.
19(3), 583–588 (1974)
2. Milstein, G.N.: Numerical Integration of Stochastic Differential Equations. Kluwer Academic
Publ, Dordrecht (1995)
3. Milshtein, G.N., Tretyakov, M.V.: Stochastic Numerics for Mathematical Physics. Springer,
Berlin (2004)
4. Kloeden, P.E., Platen, E.: Numerical Solution of Stochastic Differential Equations. Springer,
Berlin (1992)
5. Kuznetsov, D.F.: A method of expansion and approximation of repeated stochastic Stratonovich
integrals based on multiple Fourier series on full ortonormal systems. Diff. Eqn. Control
Process. (1), 18–77 (in Russian) (1997)
6. Prigarin, S.M., Belov, S.M.: One Application of Series Expansions of Wiener Process. Preprint
1107. ICM & MG Publ., Novosibirsk, Russia (in Russian) (1998)
7. Wiktorsson, M.: Joint characteristic function and simultaneous simulation of iterated Ito
integrals for multiple independent Brownian motions. Ann. Appl. Probab. 11(2), 470–487
(2001)
8. Ryden, T., Wiktorsson, M.: On the simulation of iterated Itô integrals. Stoch. Process Their
Appl. 91(1), 151–168 (2001)
9. Tang, X., Xiao, A.: Asymptotically optimal approximation of some stochastic integrals and its
applications to the strong second-order methods. Adv. Comput. Math. 45(3), 813–846 (2019)
10. Rybakov, K.A.: Applying spectral form of mathematical description for representation of
iterated stochastic integrals. Diff. Eqn. Control Process. (4), 1–31 (in Russian) (2019)