

Statistical Modelling and Variable Selection in Climate Science
361
So next we consider the test of null hypothesis about individual regression coefficients. To test the null hypothesis H 0 : β j = 0 versus the alternative hypothesis
H 1 : β j = 0, j = 0, 1, 2, …, k, the corresponding test statistic is t =
ˆ
β j
√ ˆ
σ 2 C j j
, which
follows a t distribution with (n − k − 1) degrees of freedom under H 0 . The decision
rule is to reject H 0 at α level of significance if p-value is smaller than α. If H 0 : β j = 0
is accepted, then the term X j β j in (1) becomes X j × 0 = 0, which indicates as if the
jth explanatory variable X j is absent in the model or in other words, the contribution
of X j is negligible and hence X j can be treated as an irrelevant variable. Thus this
test indicates the contribution of X j in modelling the relationship given the other
explanatory variables in the model.
2.5 Coefficient of Determination (R 2 ) and Adjusted R 2
Once a model is fitted based on suitably chosen explanatory variables, it is required to
know how good is the fitted model. The quantification of goodness of fit is achieved
by the coefficient of determination, which is based on the use of multiple correlation
coefficient between y and X 1 , X 2 , . . . , X k denoted as R
2 . The square of multiple
correlation coefficient (R
2
) is called as coefficient of determination, which describes
the degree of goodness of fit of the regression line obtained on the basis of a sample
of data.
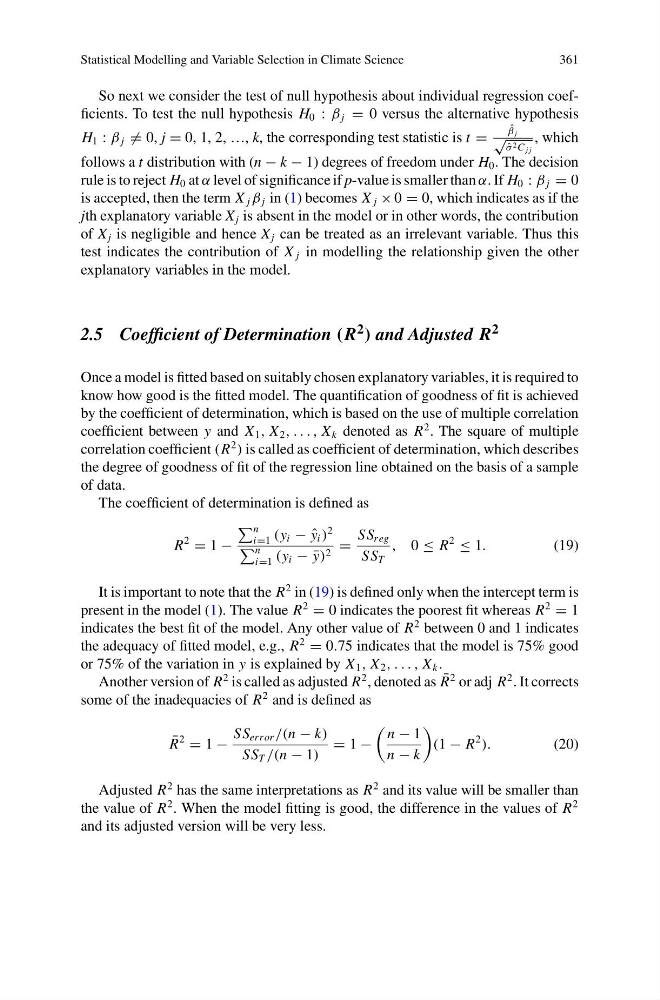
The coefficient of determination is defined as
R
2
= 1 −
n
i=1 (y i − ˆ
y i )
2
n
i=1 (y i − ¯
y) 2 =
SS reg
SS T
, 0 ≤ R
2
≤ 1.
(19)
It is important to note that the R
2 in (19) is defined only when the intercept term is
present in the model (1). The value R
2
= 0 indicates the poorest fit whereas R
2
= 1
indicates the best fit of the model. Any other value of R
2 between 0 and 1 indicates
the adequacy of fitted model, e.g., R
2
= 0.75 indicates that the model is 75% good
or 75% of the variation in y is explained by X 1 , X 2 , . . . , X k .
Another version of R
2 is called as adjusted R
2 , denoted as ¯
R
2 or adj R
2 . It corrects
some of the inadequacies of R
2 and is defined as
¯
R
2
= 1 −
SS err or /(n − k)
SS T /(n − 1)
= 1 −
n − 1
n − k
(1 − R
2
).
(20)
Adjusted R
2 has the same interpretations as R
2 and its value will be smaller than
the value of R
2 . When the model fitting is good, the difference in the values of R
2
and its adjusted version will be very less.