

There are several types of kriging techniques. Ordinary Kriging (OK) that
estimates the weighted averages of neighboring data attributes. This model assumes
no trend in the data. Data should have the following three requirements for OK:
• Trend function should be constant
• Variogram should be constant over the study area
• Data should have a normal distribution
Regression kriging (RK) combines regression and kriging by treating these as two
separate, consecutive steps Heuvelink (2014). The regression step applies multiple
linear regression. Next, a kriging step is performed in which the regression residual
is no longer treated as uncorrelated but is allowed to be spatially correlated. Thus,
simple kriging, in which it can be assumed that the residual mean is known, is
applied to the residuals. Finally, the kriged residual is added to the regression result.
Universal kriging (UK) uses the same underlying statistical model as RK; however, unlike RK, estimation of the trend and kriging of the residuals are integrated.
This is more attractive from a theoretical point of view because when residuals are
correlated, this influences the optimal estimation of the regression coefficients
ignored in RK. An additional advantage of the OK over RK is that computation of
the prediction error also takes the estimation error of the regression coefficients into
account as well as the correlation between these errors and the residual interpolation
error.
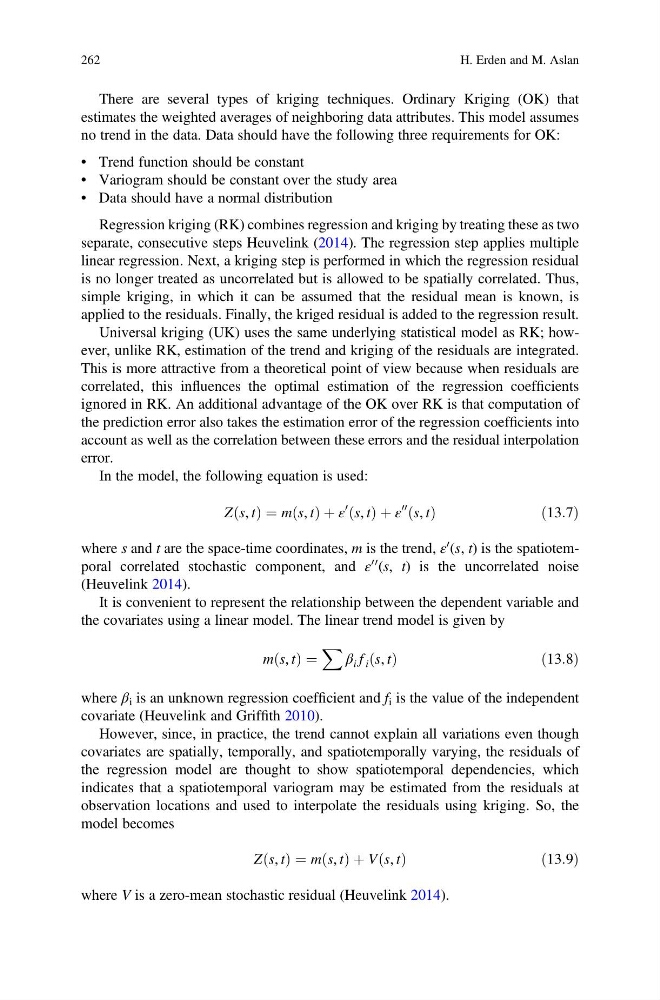
In the model, the following equation is used:
Z s, t
ð Þ ¼ m s, t
ð Þ þ ε
0 s, t
ð Þ þ ε
00 s, t
ð Þ
ð13:7Þ
where s and t are the space-time coordinates, m is the trend, ε
0 (s, t) is the spatiotemporal correlated stochastic component, and ε
00 (s, t) is the uncorrelated noise
(Heuvelink 2014).
It is convenient to represent the relationship between the dependent variable and
the covariates using a linear model. The linear trend model is given by
m s, t
ð Þ ¼
X β i f i s, t
ð Þ
ð13:8Þ
where β i is an unknown regression coefficient and f i is the value of the independent
covariate (Heuvelink and Griffith 2010).
However, since, in practice, the trend cannot explain all variations even though
covariates are spatially, temporally, and spatiotemporally varying, the residuals of
the regression model are thought to show spatiotemporal dependencies, which
indicates that a spatiotemporal variogram may be estimated from the residuals at
observation locations and used to interpolate the residuals using kriging. So, the
model becomes
Z s, t
ð Þ ¼ m s, t
ð Þ þ V s, t
ð Þ
ð13:9Þ
where V is a zero-mean stochastic residual (Heuvelink 2014).
262
H. Erden and M. Aslan