

186
STATISTICAL RESPONSES FOR LINEAR STRUCTURES
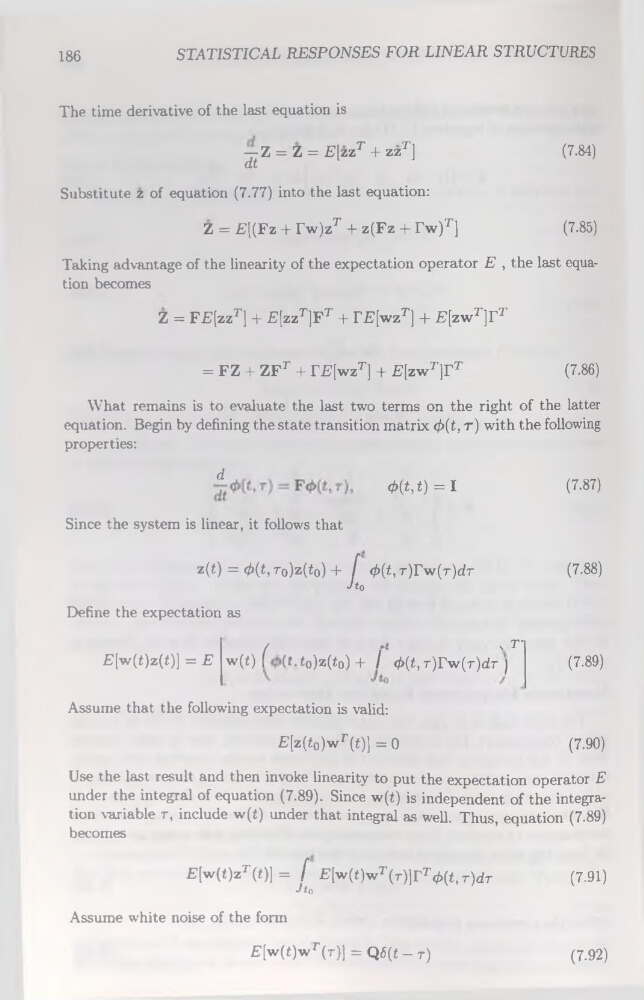
The time dérivative of the last équation is
— Z = Z = E[zzT + zzT]
(7.84)
dt
'
Substitute z of équation (7.77) into the last équation:
Z = E[(Fz + fw)zT + z(Fz + rw)T]
(7.85)
Taking advantage of the linearity of the expectation operator E , the last équation becomes
Z = FE[zzr] + E[zzt]Ft + TE[wzt] + E[zwt]Tt
= FZ + ZFr + TE[wzt] + E[zwr]rT
(7.86)
What remains is to evaluate the last two terms on the right of the latter
équation. Begin by defining the State transition matrix (t, r) with the following
properties:
d
0(t,t) = I
Since the System is linear, it follows that
z(t) = 0(t,TO)z(tO) + /" (^,T)rw(r)dT
Jto
Define the expectation as
(7.87)
(7.88)
£?[w(t)z(t)] = E
(
'T'
w(t) ( (t.t0)z(t0) + / ^>(f,r)rw(T)dr |
(7.89)
Assume that the following expectation is valid:
E[z(t0)wr(t)] =0
(7.90)
Use the last resuit and then invoke linearity to put the expectation operator E
under the intégral of équation (7.89). Since w(t) is independent of the intégration variable t, include w(t) under that integra] as well. Thus, équation (7.89)
becomes
E[w(t)zr(t)] = [ E[w(t)wr(r)]rT(t, r)dr
J ÉQ
(7.91)
Assume white noise of the form
E[w(t)wr(r)] = Qô(t-r)
(7.92)