

536
ANDREAS OSCHLIES
problem, with the constraint being the model dynamics. Weakconstraint variational methods, on the other hand, allow for some
certainty in the model dynamics and do not require that the “best”
trajectory is an exact solution of the model equations [Losa et al., 2004].
In principle, the uncertainty in the model dynamics can also be
counted for by the strong-constraint method: by explicitly introducing
error terms that can be turned on or off by adjustable parameters to be
optimised during the optimisation process, a strong-constraint method
can also account for (and quantify) model errors. For this reason, only
strong-constraint variational methods will be discussed here.
The clue to solving constrained optimisation problems is to identify
the so-called control parameters on which the solution, or trajectory, of
the dynamical model depends. Such parameters may be initial conditions, boundary conditions (e.g., nutrient supply from outside the model
domain), or internal model parameters (e.g., maximum growth rates,
mortality rates). Together, they form a control parameter vector p,
and any particular choice of p will, for the model under consideration,
uniquely determine the temporal evolution of the model trajectory. The
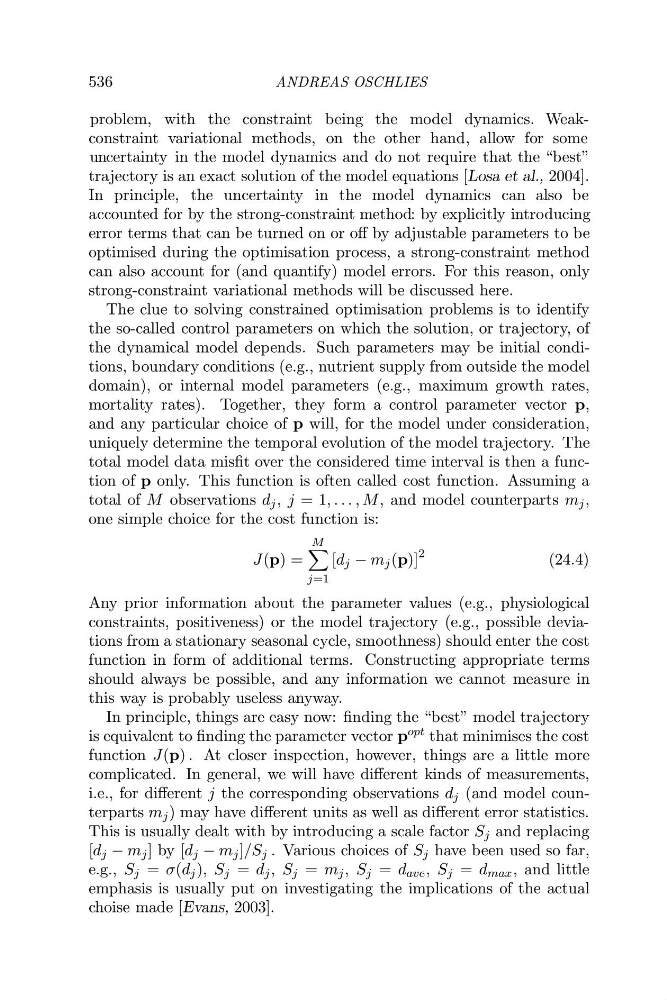
total model data misfit over the considered time interval is then a function of p only. This function is often called cost function. Assuming a
total of M observations d j , j = 1, . . . , M, and model counterparts m j ,
one simple choice for the cost function is:
J(p) =
M
j=1
[d j − m j (p)]
2
(24.4)
Any prior information about the parameter values (e.g., physiological
constraints, positiveness) or the model trajectory (e.g., possible deviations from a stationary seasonal cycle, smoothness) should enter the cost
function in form of additional terms. Constructing appropriate terms
should always be possible, and any information we cannot measure in
this way is probably useless anyway.
In principle, things are easy now: finding the “best” model trajectory
is equivalent to finding the parameter vector p opt that minimises the cost
function J(p) . At closer inspection, however, things are a little more
complicated. In general, we will have different kinds of measurements,
i.e., for different j the corresponding observations d j (and model counterparts m j ) may have different units as well as different error statistics.
This is usually dealt with by introducing a scale factor S j and replacing
[d j − m j ] by [d j − m j ]/S j . Various choices of S j have been used so far,
e.g., S j = σ(d j ), S j = d j , S j = m j , S j = d ave , S j = d max , and little
emphasis is usually put on investigating the implications of the actual
choise made [Evans, 2003].
n
u
c
a