

146
Chapter 8: Statistical Analysis of GCM Output
known, 'E should replace E in (8.9); the test statistic is then also distributed
as a X~ variable when Ho is true.
The generalization to the two-sample case is straightforward. If nx and ny
are independent observations of two random m-dimensional normal variables
X and Y with the same covariance matrix 'E and distribution N(jix, 'E) and
N(jiy, 'E), respectively, the null hypothesis jix = jiy can be tested when
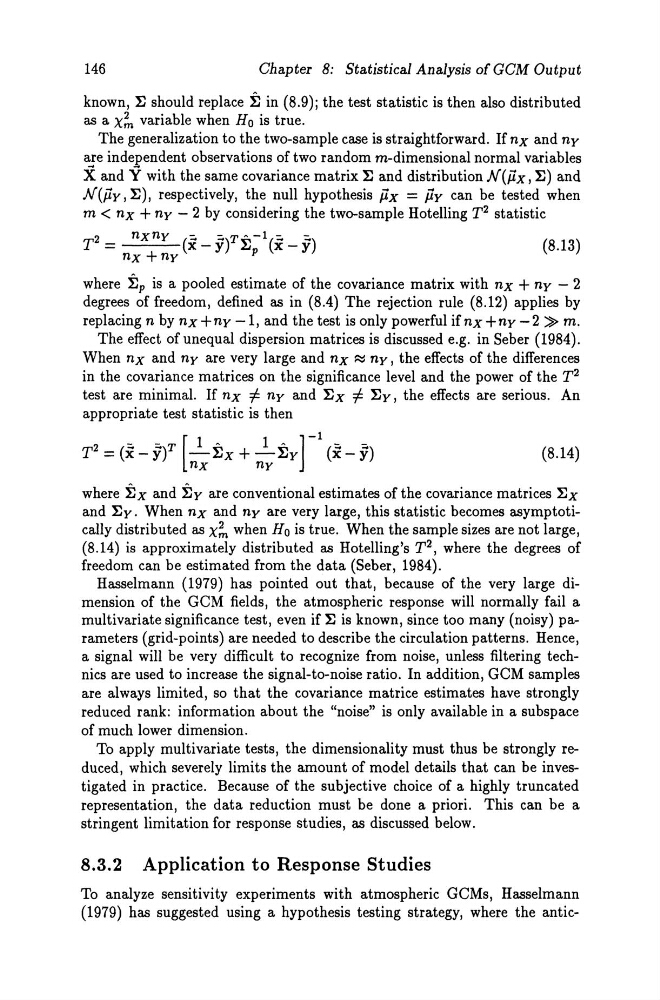
m< nx + ny - 2 by considering the two-sample Hotelling T 2 statistic
T 2 = nxny (i _ y)TE-\i - y)
(8.13)
nx + ny
P
where Ep is a pooled estimate of the covariance matrix with nx + ny - 2
degrees of freedom, defined as in (8.4) The rejection rule (8.12) applies by
replacing n by nx + ny -1, and the test is only powerful if nx + ny - 2 ~ m.
The effect of unequal dispersion matrices is discussed e.g. in Seber (1984).
When nx and ny are very large and nx ~ ny, the effects of the differences
in the covariance matrices on the significance level and the power of the T2
test are minimal. If nx =F ny and 'Ex =F 'Ey, the effects are serious. An
appropriate test statistic is then
2
-
- T [ 1· 1.] -1 - -
T =(x-y) -'Ex+-'Ey
(x-y)
nx
ny
(8.14)
where Ex and Ey are conventional estimates of the covariance matrices ~x
and ~y. When nx and ny are very large, this statistic becomes asymptotically distributed as x~ when Ho is true. When the sampie sizes are not large,
(8.14) is approximately distributed as Hotelling's T2, where the degrees of
freedom can be estimated from the data (Seber, 1984).
Hasselmann (1979) has pointed out that, because of the very large dimension of the GCM fields, the atmospheric response will normally fail a
multivariate significance test, even if ~ is known, since too many (noisy) parameters (grid-points) are needed to describe the circulation patterns. Hence,
a signal will be very difficult to recognize from noise, unless filtering technies are used to increase the signal-to-noise ratio. In addition, GCM sampies
are always limited, so that the covariance matrice estimates have strongly
reduced rank: information about the "noise" is only available in a subspace
of much lower dimension.
To apply multivariate tests, the dimensionality must thus be strongly reduced, which severely limits the amount of model details that can be investigated in practice. Because of the subjective choice of a highly truncated
representation, the data reduction must be done apriori. This can be a
stringent limitation for response studies, as discussed below.
8.3.2 Application to Response Studies
To analyze sensitivity experiments with atmospheric GCMs, Hasselmann
(1979) has suggested using a hypothesis testing strategy, where the antic-