

7.2. Model Calibration and Parameter Estimation
203
the continued involvement of the modeler. In addition, it cannot guarantee
convergence to the optimal parameters.
In order to realize the "automatization" of computation, we have to determine a criterion for measuring the "distance" between the observations of
Eq. (7.2.1) and the model outputs of Eq. (7.2.3). The most commonly adopted
one is the criterion of least squares, that is
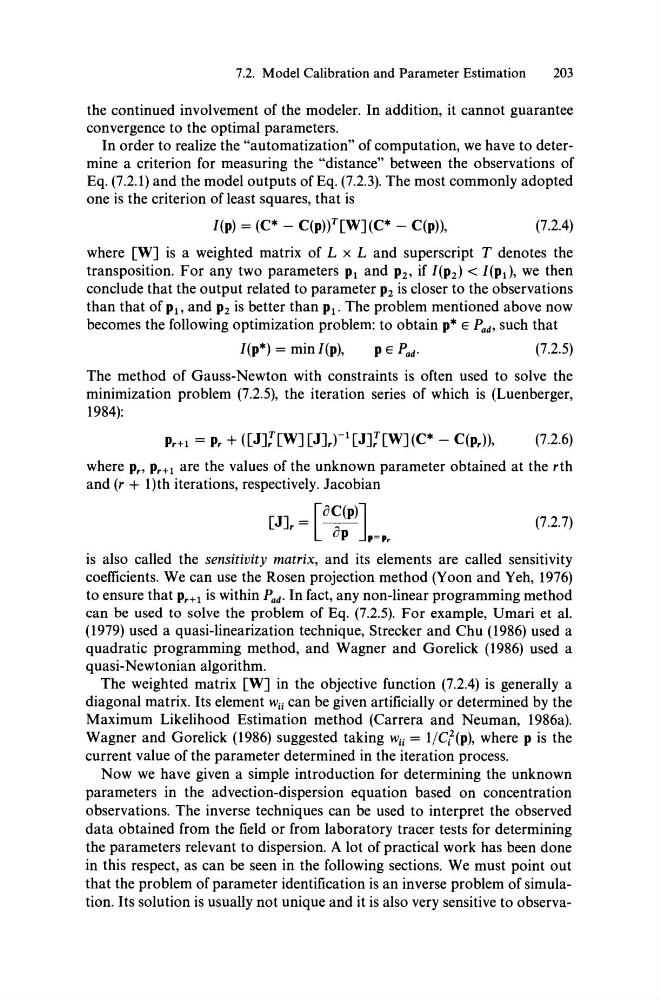
I(p) = (C* - C(pW[W](C* - C(p»,
(7.2.4)
where [W] is a weighted matrix of L x Land superscript T denotes the
transposition. For any two parameters PI and P2' if I(P2) < I(pd, we then
conclude that the output related to parameter P2 is closer to the observations
than that of PI' and P2 is better than PI. The problem mentioned above now
becomes the following optimization problem: to obtain p* E P ad , such that
I(p*) = min I(p),
pE P ad •
(7.2.5)
The method of Gauss-Newton with constraints is often used to solve the
minimization problem (7.2.5), the iteration series of which is (Luenberger,
1984):
Pr+l = Pr + ([J];[WJ [J],t l [J];[W] (C* - C(Pr»'
(7.2.6)
where Pr' Pr+l are the values of the unknown parameter obtained at the rth
and (r + l)th iterations, respectively. Jacobian
[J], = [aC(p)]
ap '=Pr
(7.2.7)
is also called the sensitivity matrix, and its elements are called sensitivity
coefficients. We can use the Rosen projection method (Yoon and Yeh, 1976)
to ensure that Pr+l is within Pad• In fact, any non-linear programming method
can be used to solve the problem of Eq. (7.2.5). For example, Umari et al.
(1979) used a quasi-linearization technique, Strecker and Chu (1986) used a
quadratic programming method, and Wagner and Gorelick (1986) used a
quasi-Newtonian algorithm.
The weighted matrix [W] in the objective function (7.2.4) is generally a
diagonal matrix. Its element Wii can be given artificially or determined by the
Maximum Likelihood Estimation method (Carrera and Neuman, 1986a).
Wagner and Gorelick (1986) suggested taking W ii = I/C i 2 (p), where P is the
current value of the parameter determined in the iteration process.
Now we have given a simple introduction for determining the unknown
parameters in the advection-dispersion equation based on concentration
observations. The inverse techniques can be used to interpret the observed
data obtained from the field or from laboratory tracer tests for determining
the parameters relevant to dispersion. A lot of practical work has been done
in this respect, as can be seen in the following sections. We must point out
that the problem of parameter identification is an inverse problem of simulation. Its solution is usually not unique and it is also very sensitive to observa-