

40
3 Finite-Time Robust Filtering for Multi-model Jumping System
where
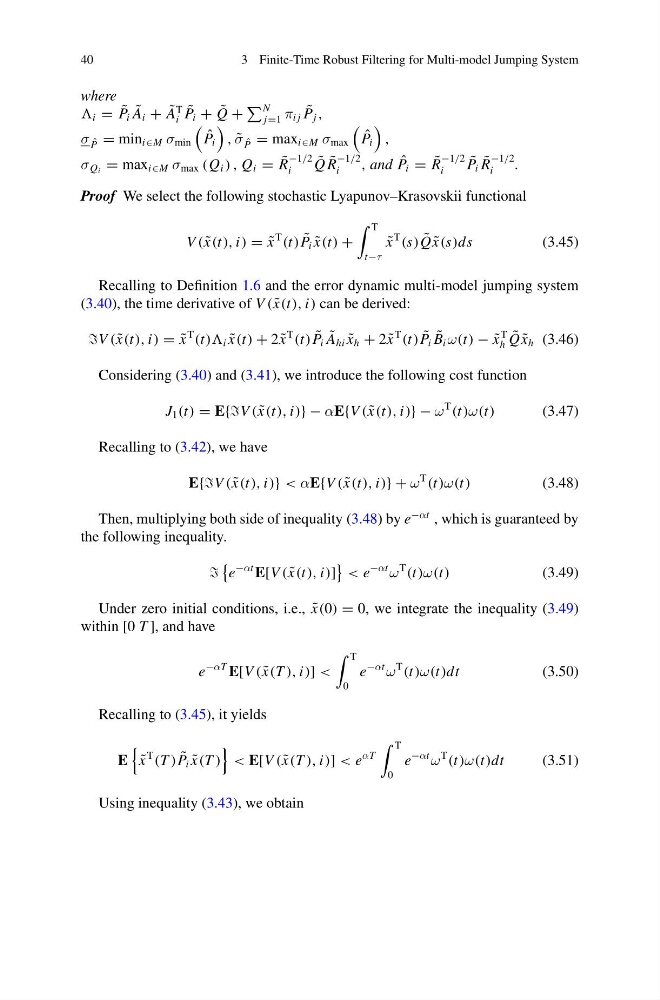
i = ˜
P i ˜
A i + ˜
A
T
i
˜
P i + ˜
Q +
N
j=1 π i j ˜
P j ,
σ ˆ
P = min i∈M σ min
ˆ
P i
, ˜
σ ˆ
P = max i∈M σ max
ˆ
P i
,
σ Q i = max i∈M σ max (Q i ) , Q i = ˜
R
−1/2
i
˜
Q ˜
R
−1/2
i
, and ˆ
P i = ˜
R
−1/2
i
˜
P i ˜
R
−1/2
i
.
Proof We select the following stochastic Lyapunov–Krasovskii functional
V ( ˜
x(t), i) = ˜
x
T
(t) ˜
P i ˜
x(t) +
T
t−τ
˜
x
T
(s) ˜
Q ˜
x(s)ds
(3.45)
Recalling to Definition 1.6 and the error dynamic multi-model jumping system
(3.40), the time derivative of V ( ˜
x(t), i) can be derived:
V ( ˜
x(t), i) = ˜
x
T
(t)) i ˜
x(t) + 2 ˜
x
T
(t) ˜
P i ˜
A hi ˜
x h + 2 ˜
x
T
(t) ˜
P i ˜
B i ω(t) − ˜
x
T
h
˜
Q ˜
x h (3.46)
Considering (3.40) and (3.41), we introduce the following cost function
J 1 (t) = E{{V ( ˜
x(t), i)} − αE{V ( ˜
x(t), i)} − ω
T
(t)ω(t)
(3.47)
Recalling to (3.42), we have
E{{V ( ˜
x(t), i)} < αE{V ( ˜
x(t), i)} + ω
T
(t)ω(t)
(3.48)
Then, multiplying both side of inequality (3.48) by e
−αt , which is guaranteed by
the following inequality.
e
−αt E[V ( ˜
x(t), i)]
< e
−αt
ω
T
(t)ω(t)
(3.49)
Under zero initial conditions, i.e., ˜
x(0) = 0, we integrate the inequality (3.49)
within [0 T ], and have
e
−αT E[V ( ˜
x(T ), i)] <
T
0
e
−αt
ω
T
(t)ω(t)dt
(3.50)
Recalling to (3.45), it yields
E
˜
x
T
(T ) ˜
P i ˜
x(T )
< E[V ( ˜
x(T ), i)] < e
αT
T
0
e
−αt
ω
T
(t)ω(t)dt
(3.51)
Using inequality (3.43), we obtain