

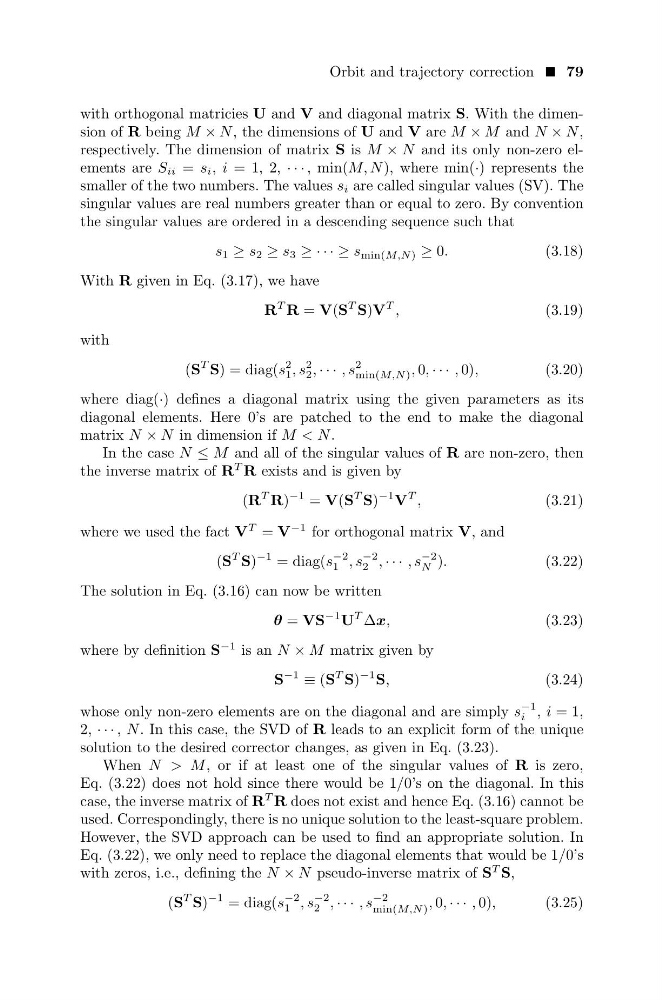
Orbit and trajectory correction 79
with orthogonal matricies U and V and diagonal matrix S. With the dimension of R being M × N , the dimensions of U and V are M × M and N × N ,
respectively. The dimension of matrix S is M × N and its only non-zero elements are S ii = s i , i = 1, 2, · · · , min(M, N ), where min(·) represents the
smaller of the two numbers. The values s i are called singular values (SV). The
singular values are real numbers greater than or equal to zero. By convention
the singular values are ordered in a descending sequence such that
s 1 ≥ s 2 ≥ s 3 ≥ · · · ≥ s min(M,N ) ≥ 0.
(3.18)
With R given in Eq. (3.17), we have
R
T R = V(S
T S)V
T ,
(3.19)
with
(S
T S) = diag(s
2
1 , s
2
2 , · · · , s
2
min(M,N ) , 0, · · · , 0),
(3.20)
where diag(·) defines a diagonal matrix using the given parameters as its
diagonal elements. Here 0’s are patched to the end to make the diagonal
matrix N × N in dimension if M < N .
In the case N ≤ M and all of the singular values of R are non-zero, then
the inverse matrix of R
T R exists and is given by
(R
T R)
−1 = V(S
T S)
−1 V
T ,
(3.21)
where we used the fact V
T = V
−1 for orthogonal matrix V, and
(S
T S)
−1 = diag(s
−2
1 , s
−2
2 , · · · , s
−2
N ).
(3.22)
The solution in Eq. (3.16) can now be written
θ = VS
−1 U
T ∆x,
(3.23)
where by definition S
−1 is an N × M matrix given by
S
−1 ≡ (S
T S)
−1 S,
(3.24)
whose only non-zero elements are on the diagonal and are simply s
−1
i , i = 1,
2, · · · , N . In this case, the SVD of R leads to an explicit form of the unique
solution to the desired corrector changes, as given in Eq. (3.23).
When N > M , or if at least one of the singular values of R is zero,
Eq. (3.22) does not hold since there would be 1/0’s on the diagonal. In this
case, the inverse matrix of R
T R does not exist and hence Eq. (3.16) cannot be
used. Correspondingly, there is no unique solution to the least-square problem.
However, the SVD approach can be used to find an appropriate solution. In
Eq. (3.22), we only need to replace the diagonal elements that would be 1/0’s
with zeros, i.e., defining the N × N pseudo-inverse matrix of S
T S,
(S
T S)
−1 = diag(s
−2
1 , s
−2
2 , · · · , s
−2
min(M,N ) , 0, · · · , 0),
(3.25)