

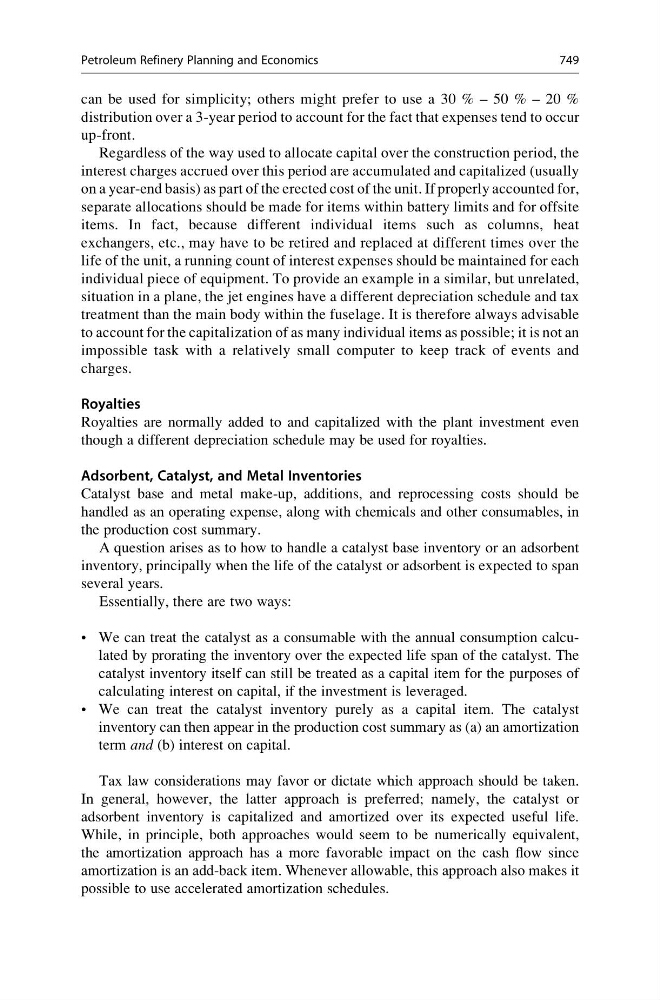
can be used for simplicity; others might prefer to use a 30 % – 50 % – 20 %
distribution over a 3-year period to account for the fact that expenses tend to occur
up-front.
Regardless of the way used to allocate capital over the construction period, the
interest charges accrued over this period are accumulated and capitalized (usually
on a year-end basis) as part of the erected cost of the unit. If properly accounted for,
separate allocations should be made for items within battery limits and for offsite
items. In fact, because different individual items such as columns, heat
exchangers, etc., may have to be retired and replaced at different times over the
life of the unit, a running count of interest expenses should be maintained for each
individual piece of equipment. To provide an example in a similar, but unrelated,
situation in a plane, the jet engines have a different depreciation schedule and tax
treatment than the main body within the fuselage. It is therefore always advisable
to account for the capitalization of as many individual items as possible; it is not an
impossible task with a relatively small computer to keep track of events and
charges.
Royalties
Royalties are normally added to and capitalized with the plant investment even
though a different depreciation schedule may be used for royalties.
Adsorbent, Catalyst, and Metal Inventories
Catalyst base and metal make-up, additions, and reprocessing costs should be
handled as an operating expense, along with chemicals and other consumables, in
the production cost summary.
A question arises as to how to handle a catalyst base inventory or an adsorbent
inventory, principally when the life of the catalyst or adsorbent is expected to span
several years.
Essentially, there are two ways:
• We can treat the catalyst as a consumable with the annual consumption calculated by prorating the inventory over the expected life span of the catalyst. The
catalyst inventory itself can still be treated as a capital item for the purposes of
calculating interest on capital, if the investment is leveraged.
• We can treat the catalyst inventory purely as a capital item. The catalyst
inventory can then appear in the production cost summary as (a) an amortization
term and (b) interest on capital.
Tax law considerations may favor or dictate which approach should be taken.
In general, however, the latter approach is preferred; namely, the catalyst or
adsorbent inventory is capitalized and amortized over its expected useful life.
While, in principle, both approaches would seem to be numerically equivalent,
the amortization approach has a more favorable impact on the cash flow since
amortization is an add-back item. Whenever allowable, this approach also makes it
possible to use accelerated amortization schedules.
Petroleum Refinery Planning and Economics
749